Appraisal independence rules keep loan production staff out of appraiser selection on most loans. Pitching them wastes your time.
Appraiser play · Lenders and AMCs
Appraiser marketing to lenders: reach the people who actually assign orders.
Loan officers can't pick appraisers for most loans, so marketing to them rarely brings orders. Spur helps you reach the vendor managers, chief appraisers, and appraisal desks who build panels, with a clear letter about your coverage, turnaround, and the assignments others turn down.
Free forever plan · No card · 20 property searches a month
USPSFirst-Class
Maria Ortiz, Vendor ManagerGreat Lakes Credit UnionAnn Arbor, MI 48104Scan for my credentials packet
Maria O. downloaded your credentials · 1 day ago
AI-written for this owner · Mailed in 2 days
Panelsvendor managers and appraisal desks
Coverageand specialty details on every piece
Quarterlyupdates that keep you on the list
The problem
Marketing to loan officers doesn't bring appraisal orders.
Vendor managers see hundreds of applications. A plain sign-up form doesn't tell them what you do better.
When a rural or complex order needs an appraiser fast, panel managers call the name they recall, not the best fit.
How it works
From list to mailbox in one workflow.
Five steps from a lender list to new panel assignments.
app.usespur.com
See it in Spur
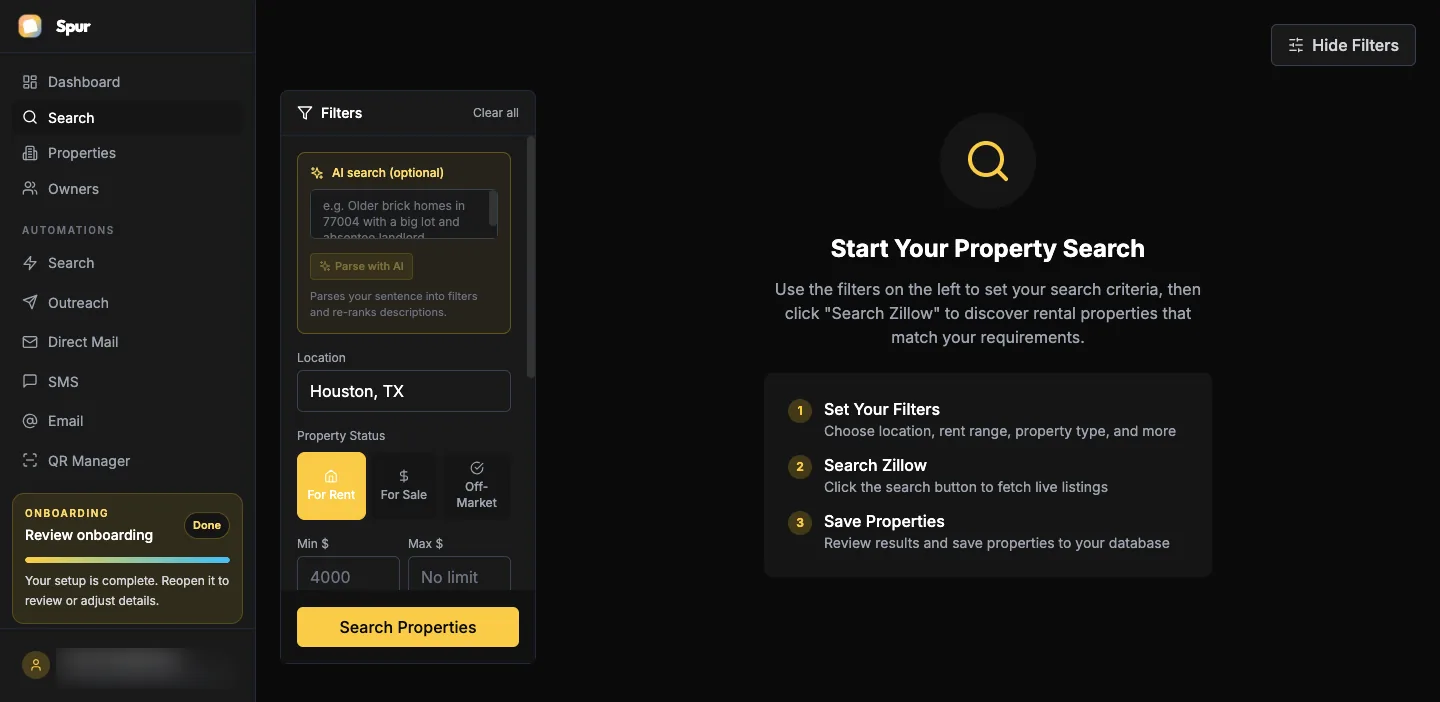
A lender and AMC list in Spur
Sample lenders and AMCs active in southeast Michigan. Names are partly masked.
Southeast MichiganAMCs + credit unions + banksCustom list uploadPanel contact known
- Maria O.Great Lakes Credit UnionVendor managerDirect panelRural need
- Appraisal deskHuron Valley BankChief appraiserCommunity bank2–4 units
- Vendor managementMidwest Valuation AMCPanel recruitingAMC6 counties
- Ken P.Peninsula Private LendingOwnerPrivate lenderInvestor loans
- Lisa M.Lakeshore Federal CULending operationsCredit unionLuxury need
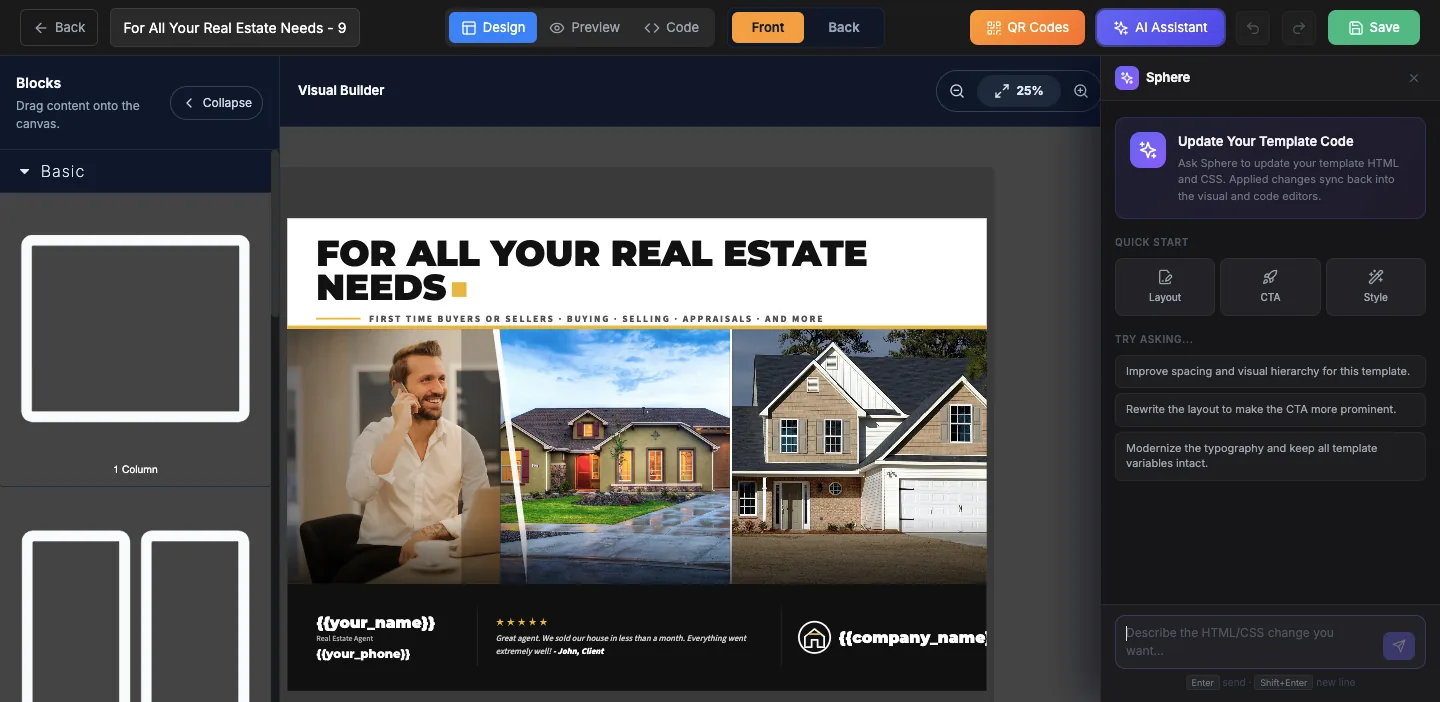
AI draft for Maria O. · Great Lakes Credit Union
Dear Ms. Ortiz,
I'm Dana Fields, a certified residential appraiser based in Ann Arbor. I'm writing to ask to be considered for Great Lakes Credit Union's appraiser panel.
I cover Washtenaw, Livingston, Monroe, Jackson, Lenawee, and Hillsdale counties, including rural acreage, 2–4 unit properties, and custom and luxury homes that can be hard to place. My average turnaround is five business days, I carry E&O insurance, and I've completed more than 1,800 appraisals over 11 years with a low revision rate.
Scan the code for my credentials packet, including my license, insurance, and sample reports. I'd be glad to help with assignments others turn down.
Dana Fields · Certified Residential Appraiser · Lic. #0000000 · (734) 555-0151
Sample data for illustration. Your results depend on your market and filters.
Playbook
How appraisers get more work from lenders
Lender work is the core of most residential appraisal businesses, but how lenders choose appraisers has changed. Appraisal independence rules separate loan production staff from appraiser selection on most mortgage loans, so many lenders assign orders through appraisal management companies or internal panels. Your marketing should reach the people who build and manage those panels: vendor managers, chief appraisers, and appraisal desk staff.
Smaller lenders are often the best opportunity. Credit unions, community banks, and private and business-purpose lenders may manage their own panels and value a reliable local appraiser. AMCs recruit constantly, especially for areas and property types where they struggle to place orders.
Lead with what panel managers screen for: your coverage area, property types, turnaround, licensing level, insurance, and quality record. Specialties matter most. Rural acreage, 2–4 unit properties, luxury and custom homes, and complex assignments are often hard to place, and appraisers who take them get remembered.
Stay within independence rules. Market your competence and availability, never a willingness to hit a value. Don't market to loan officers in ways that suggest they can direct orders to you, and don't offer anything of value to influence assignments. Include your license or certification number where your state requires it.
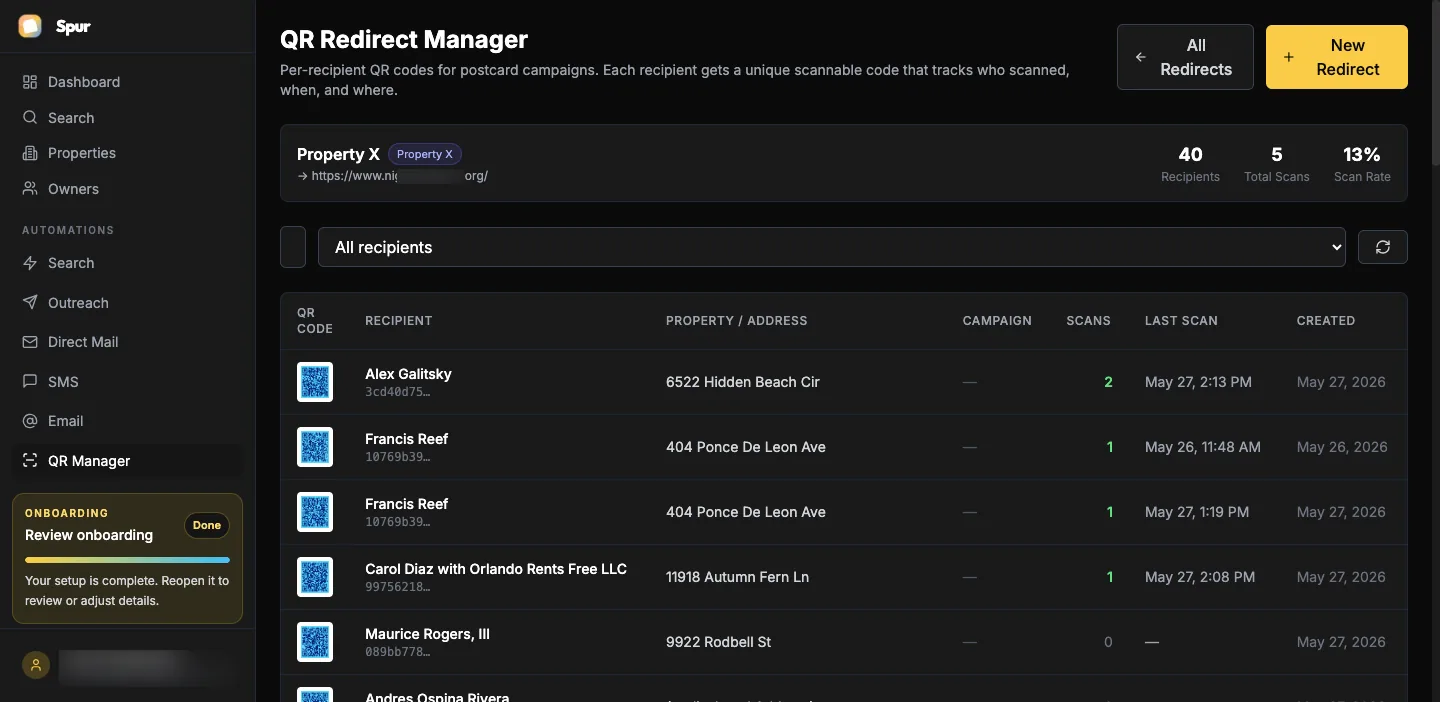
Make it easy to say yes. A credentials packet with your license, E&O certificate, sample reports, and W-9 ready to share saves panel managers time. A QR code that opens it shows you who's interested.
Then stay in touch. A short quarterly update with your coverage, turnaround, and a local market note keeps you top of mind when a difficult order needs an appraiser quickly.
Watch your scorecards once you're on a panel. Many lenders and AMCs rate appraisers on turnaround, revision requests, and communication, and those scores decide who gets the next order. Strong early performance on a new panel often matters more than any marketing you send.
36×return on a year of Spur Team from one lender client
One new lender client can fill your calendar.
- Spur Team: $588/yr billed annually
- 120 lenders and AMCs × 4 letters = 480 at $1.39 = $667
- One lender sending 4 orders a month at $450 = $21,600 a year, about 36× your subscription
Example math. Fees and order volume vary by lender, AMC, and market. Run your own numbers →
One tool, not four
Spur vs. the usual way appraisers chase panels
What you needThe usual waySpur
List of lenders and AMCs in your areaSigning up on portals one by one✓ Built in
Letter with coverage and specialtiesA generic online application✓ Built in
Credentials packet by QREmailing attachments on request✓ Built in
Delivery trackingNo signal✓ Built in
Quarterly coverage updatesHoping they remember✓ Built in
FAQ
Lender marketing questions
How do appraisers get work from lenders?
Mostly through lender panels and appraisal management companies. Market to the vendor managers and chief appraisers who build panels, not loan officers, who usually can't select appraisers.
Can I market my appraisal services to loan officers?
You can share your availability, but appraisal independence rules keep loan production staff out of appraiser selection on most loans. Don't suggest they can direct orders to you.
How do I get on more AMC panels?
Lead with coverage areas and property types they struggle to fill, keep your credentials packet ready, and follow up quarterly. AMCs recruit constantly for hard-to-serve areas.
Which lenders are most likely to add me?
Credit unions, community banks, and private lenders that manage their own panels, especially in rural areas or for complex properties.
What should I include in my lender letter?
Your coverage area, property types, turnaround, licensing level, insurance, and quality record, plus your license number where required.
Keep exploring
Related plays and guides
Start in minutes. No card required.
Be the appraiser they call for the hard orders.
Build your list of lenders and AMCs, send a clear credentials letter, and get on your next panel.
Reach lenders and AMCs — freeFree forever plan · No card · 20 property searches a month
Prefer a walkthrough? Book a demo