Purchase business depends on agents remembering you. When they get busy, your pipeline gets quiet.
For lenders and loan officers
Mortgage direct mail that finds borrowers before they shop rates.
Find high-equity homeowners, long-time owners ready to move up, and investors who need financing, then mail them a personal, compliance-reviewed postcard with a QR code to your application or calendar. Use the same tools to win referral partners among active agents.
Free forever plan · No card · 20 property searches a month
USPSFirst-Class
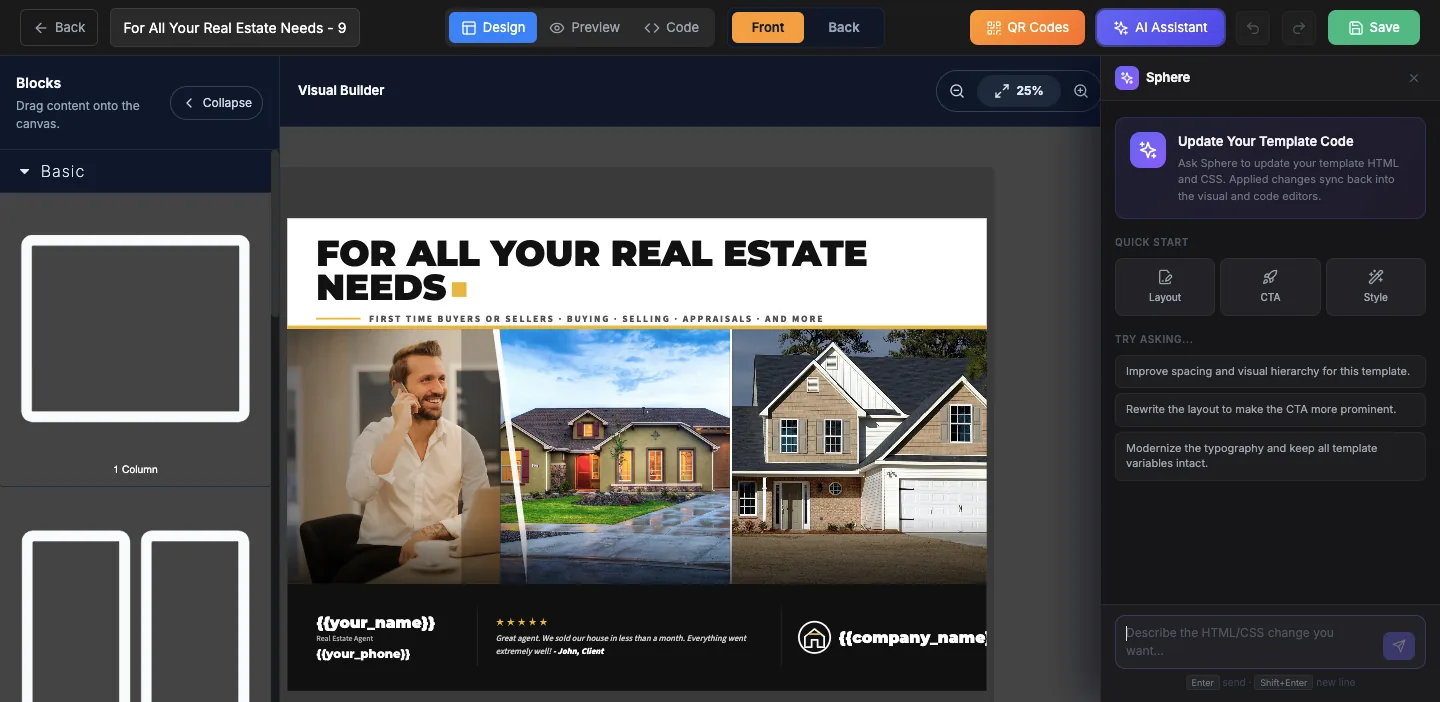
Sarah Ellis640 S Gilpin StDenver, CO 80209Scan to book a 15-min review
Sarah E. booked a consultation · 3 min ago
AI-written for this owner · Mailed in 2 days
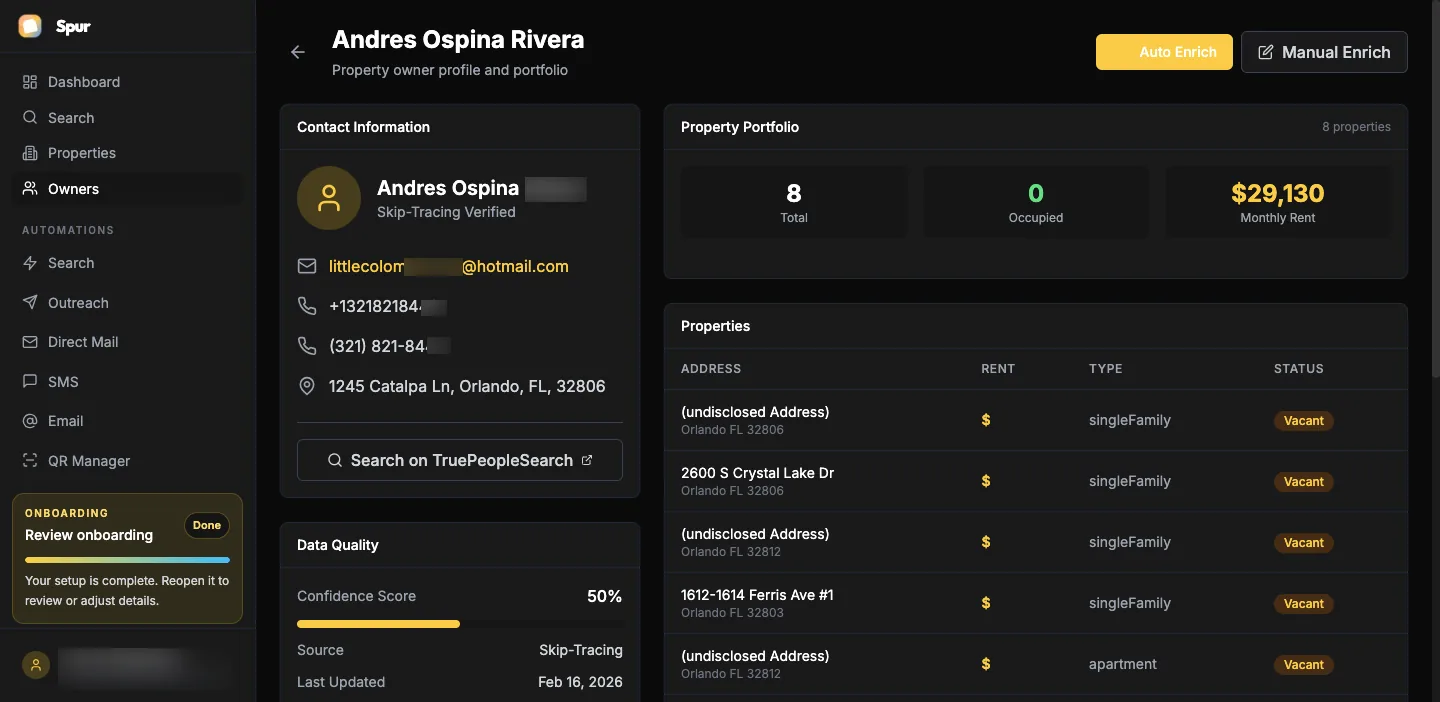
Equityand ownership-length targeting
Agentsas referral partners, not just homeowners
One reviewof your AI copy by compliance, then scale
The problem
Your pipeline depends on other people's timing.
By the time a homeowner searches online, they're comparing five lenders on rate alone.
Generic mortgage mail goes back and forth with compliance, and by the time it's approved the market has moved.
How it works
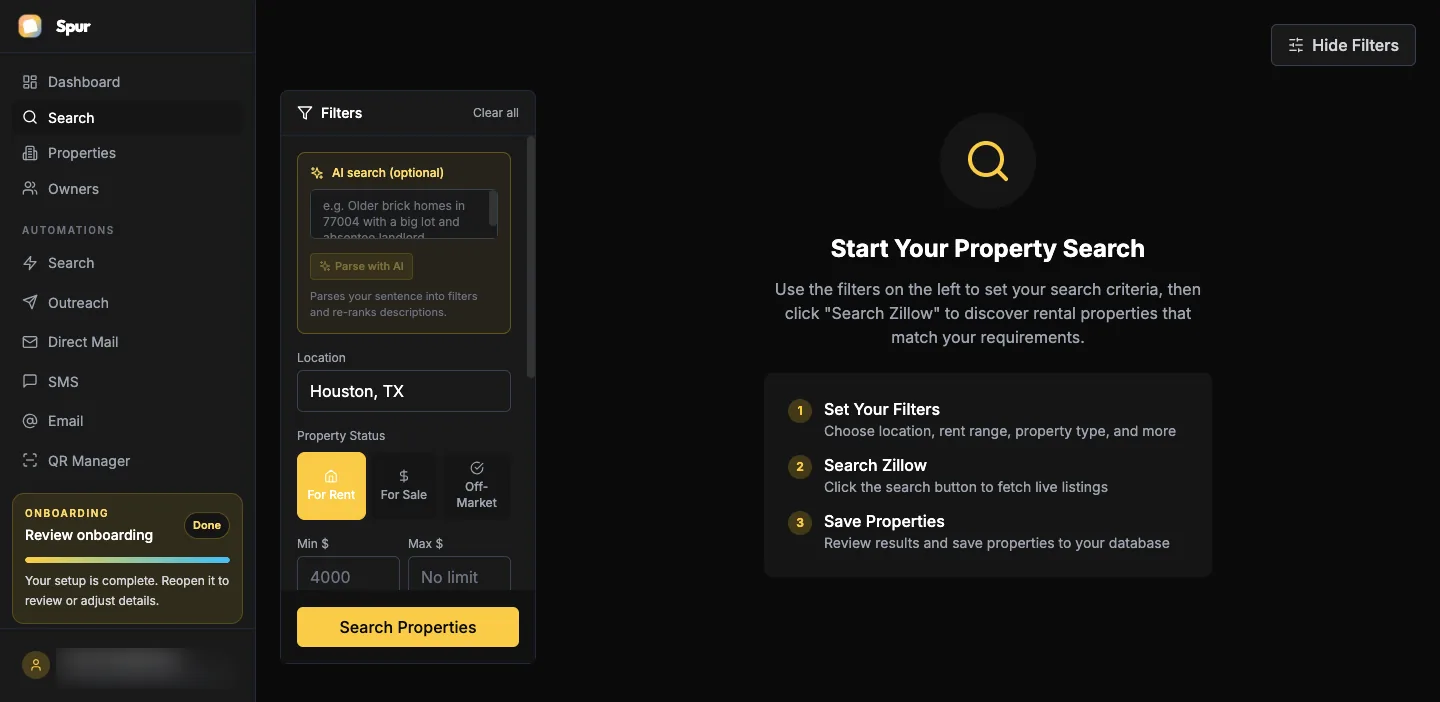
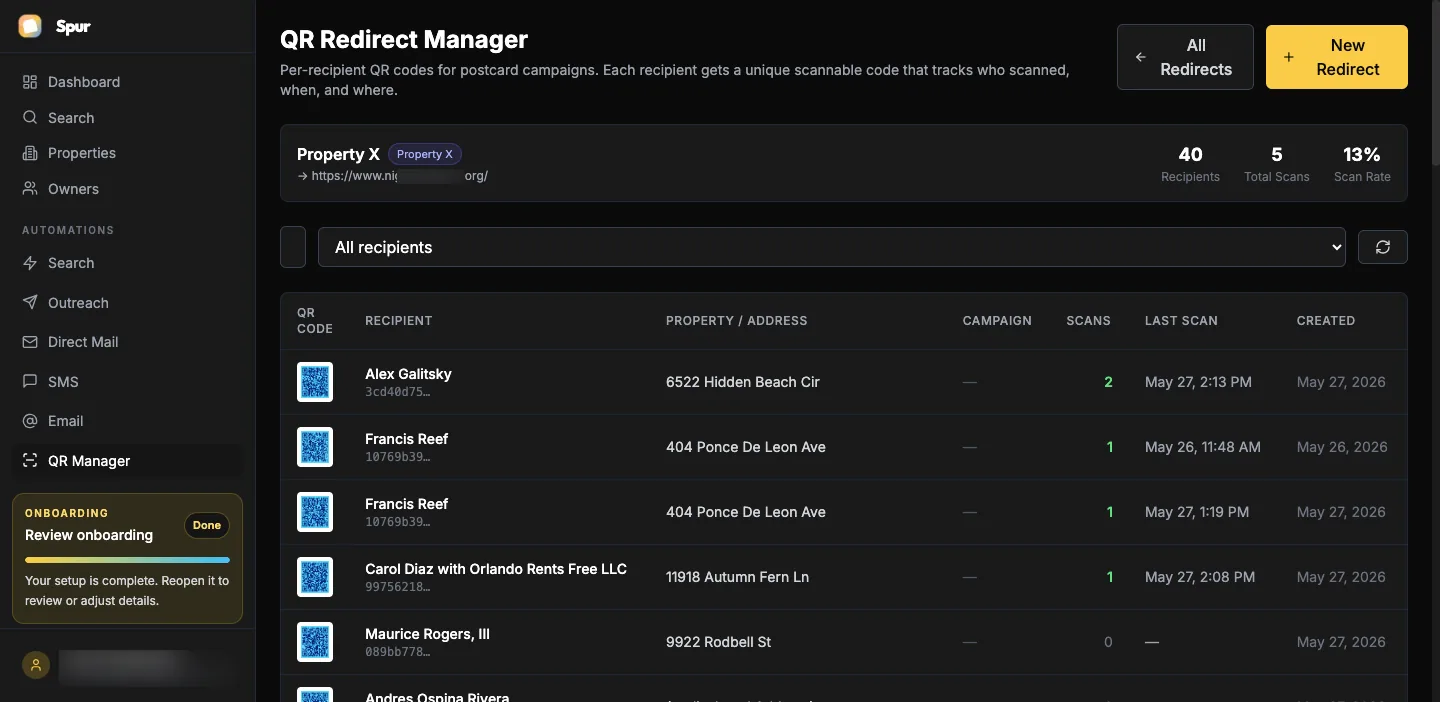
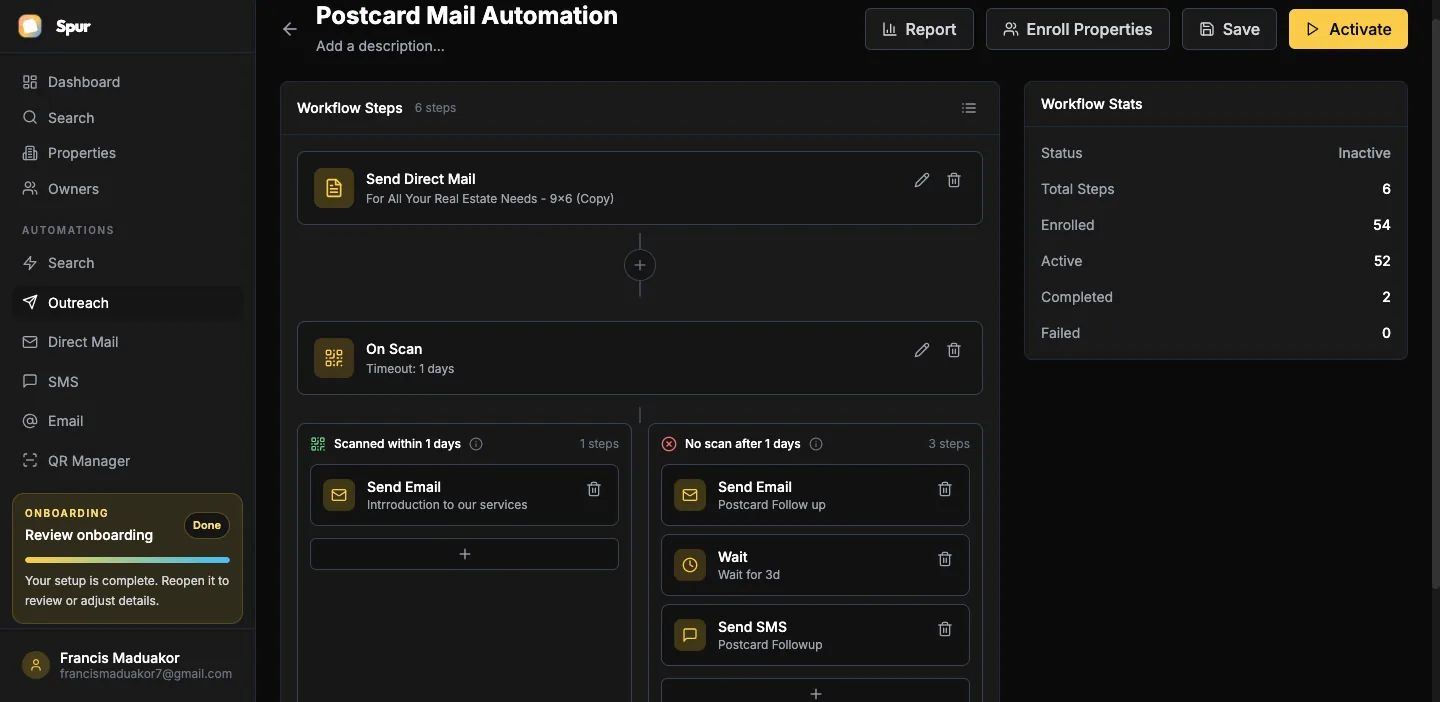
From list to mailbox in one workflow.
The same five steps every time, set up for lenders & loan officers.
app.usespur.com
Plays for Lenders
Lender plays you can run in Spur today
HELOC and cash-outMove-up buyers Reverse mortgage
Homeowners with substantial equity and a reason to tap it.
Equity 40%+Owned 7+ yrs
See the full play →Rate-and-term refinanceOwners who bought when rates were higher.
Purchased 2023–2024
See the full play →Long-time owners in appreciating areas who may upsize.
Owned 8+ yrs2–3 beds
Older long-time owners with high equity (62+ eligibility).
Owned 25+ yrsEquity 80%+
See the full play →Investor and DSCR loansRental owners who need financing for their next purchase.
AbsenteeOwns 2+ properties
See the full play →Agent referral partnersBuild relationships with agents actively closing in your market.
Agent listZip code
See the full play →Cash-out refinanceHigh-equity owners with no loan or a higher rate.
Equity 50%+No loan or 2023–24
See the full play →Hard moneyActive flippers who need fast purchase and rehab funding.
Bought + resoldLLC
See the full play →FHA MIP removalFHA borrowers who may now have 20% equity.
FHA loanEquity 20%+
See the full play →See it in Spur
A loan officer's equity list in Spur
Sample results for long-held, high-equity homeowners in one zip code. Names are partly masked.
Zip 80209Owner-occupiedOwned 8+ yrsEquity 50%+
- Sarah E.640 S Gilpin StPurchased 2014Est. 58% equity
- Mark & Dana P.1120 S Vine StPurchased 2011Est. 66% equity
- Yolanda R.455 S Franklin StPurchased 1998Est. 92% equityOwned 28 yrs
- Brian T.903 E Ohio AvePurchased 2016Est. 51% equity
- Ken & Alice W.780 S Race StPurchased 2009Est. 71% equity
AI draft for Sarah E. · 640 S Gilpin St
Hi Sarah,
Homes in Washington Park have appreciated significantly since you bought on South Gilpin in 2014, so you may have more equity than you realize.
Homeowners in your position often use that equity to renovate, consolidate higher-interest debt, or buy their next home. Every situation is different, and the right option depends on your goals and current loan.
If you'd like a no-cost, 15-minute review of your options, scan the code to pick a time. There's no obligation to apply.
James Rivera · Mile High Lending · NMLS #000000 · Equal Housing Lender
Sample data for illustration. Your results depend on your market and filters.
Playbook
How loan officers use direct mail without the compliance headaches
Direct mail lets loan officers reach homeowners before they start comparing lenders online. Instead of competing on rate with a stranger, you're starting a conversation with someone who heard from you first, about their own home.
Choose the segment by the loan you want to write. High-equity, long-time owners are natural HELOC and cash-out candidates. Owners who bought when rates were higher are refinance candidates when rates fall. Long-time owners of smaller homes in appreciating areas are move-up buyers. Investors who own several rentals may need DSCR or portfolio financing.
Mortgage advertising is regulated, and mail is advertising. Under federal rules, stating certain terms like a payment amount or down payment can trigger required disclosures, and all mortgage ads must avoid misleading claims. Include your NMLS ID and Equal Housing language, avoid quoting rates unless your compliance team has approved the disclosures, and keep a record of what you mailed. Have compliance approve your messaging before you scale.
Agent outreach is the other half. Agents who are actively listing in your market are your best referral sources. A personal, physical letter that offers something concrete, like fast pre-approvals, co-marketing, or market updates for their clients, stands out from the emails every LO sends.
6×return on a year of Spur Team from one $350,000 loan
One loan covers your marketing for years.
- Spur Team: $588/yr billed annually
- One $350,000 loan at 100 bps compensation = $3,500
- One closed loan covers your subscription about 6× over
Example math. Compensation structures vary by lender and channel. Run your own numbers →
One tool, not four
Spur vs. the usual loan officer marketing stack
What you needThe usual waySpur
Homeowner equity dataTrigger leads or list brokers✓ Built in
Agent referral outreachNetworking events, cold email✓ Built in
CopyGeneric templates, slow compliance cycles✓ Built in
Printing and mailingMail house with minimums✓ Built in
Follow-upSeparate CRM✓ Built in
From Lenders using Spur
Results from the mailbox.
“I targeted high-equity homeowners in three zip codes with AI postcards about cash-out refi options. Got 14 inbound inquiries in the first month. Closed 3 loans.”
“I send personalized postcards to active listing agents in my market every month. I've built more referral relationships in 6 months with Spur than in 2 years of networking events.”
FAQ
Questions from lenders & loan officers
Is Spur compliant for mortgage advertising?
Spur gives you full control of the copy, and you approve every piece before it's mailed. Compliance with mortgage advertising rules (NMLS ID, Equal Housing statements, trigger-term disclosures) is your responsibility, so have your compliance team approve your templates and messaging first.
Can I target homeowners by equity?
Yes. Filter by estimated equity, ownership length, property value, and zip code to build HELOC, cash-out, or move-up lists.
Can I use Spur to market to real estate agents?
Yes. Many LOs use Spur to send personal introductions and monthly updates to active agents in their market to build referral relationships.
Is this the same as trigger leads?
No. Trigger leads come from credit inquiries and are sold to many lenders at once. Spur lets you reach homeowners based on property and ownership data, before they apply anywhere.
Can private and hard money lenders use Spur?
Yes. Target investors who own several properties or are actively buying, and mail them an introduction to your loan products.
Keep exploring
Related roles and guides
Start in minutes. No card required.
Your next borrower already owns a home. Reach them first.
Build an equity list in your market and send your first compliance-approved postcard today.
Build my borrower pipeline — freeFree forever plan · No card · 20 property searches a month
Prefer a walkthrough? Book a demo