When a homeowner applies anywhere, their credit pull can be sold as a trigger lead, and every buyer of that lead calls them at once.
Lender play · Refinance
Refinance leads: reach the owners who bought at the top of the rate cycle.
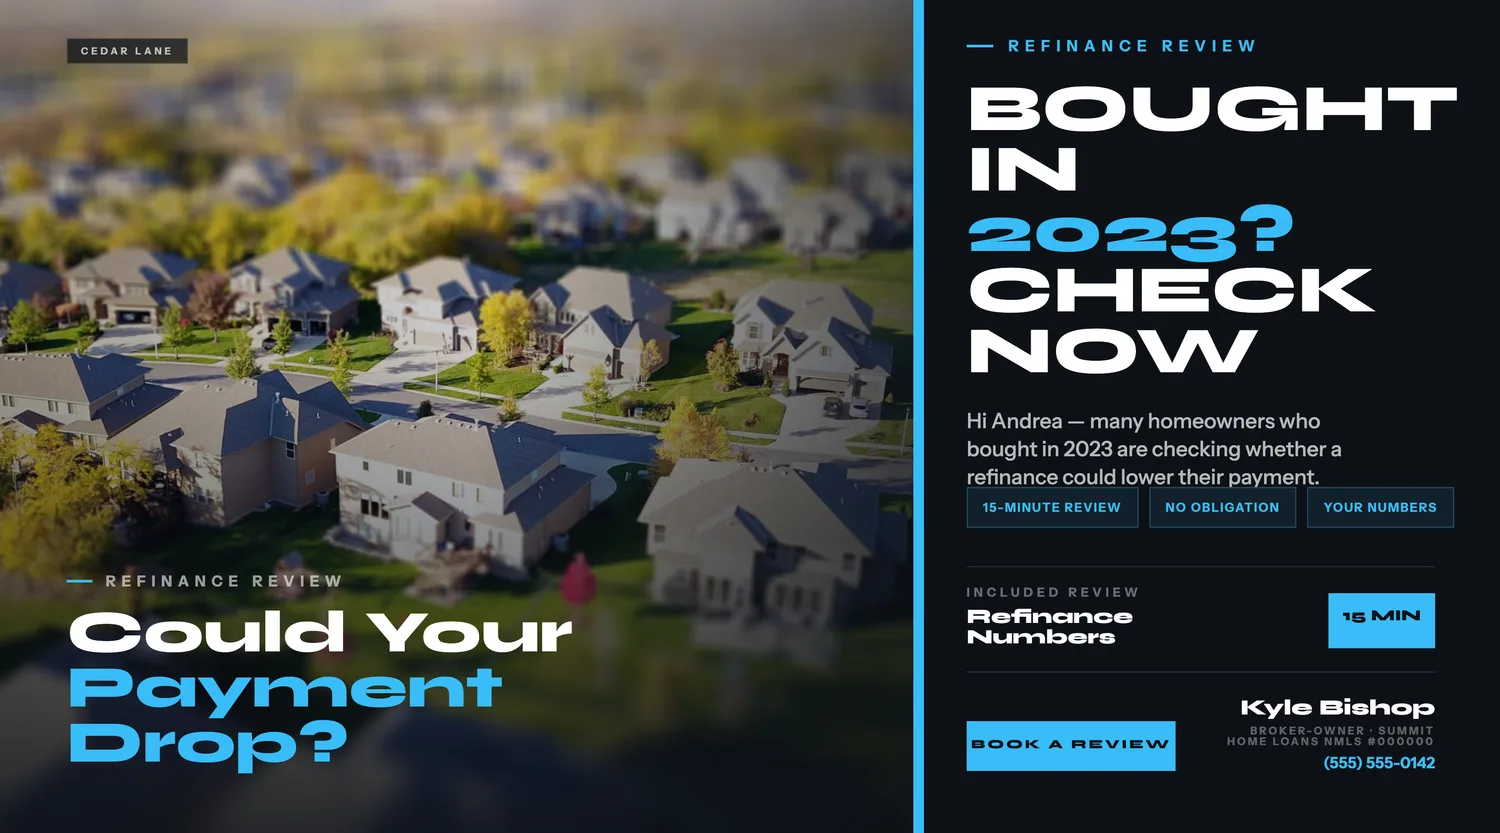
Homeowners who bought or refinanced when rates were high are the first to benefit when rates fall. Spur finds owners by purchase and loan date, reaches them before they start shopping, and mails a compliance-reviewed letter that invites them to check whether a refinance makes sense.
Free forever plan · No card · 20 property searches a month
Andrea L. booked a refinance review · 1 hr ago
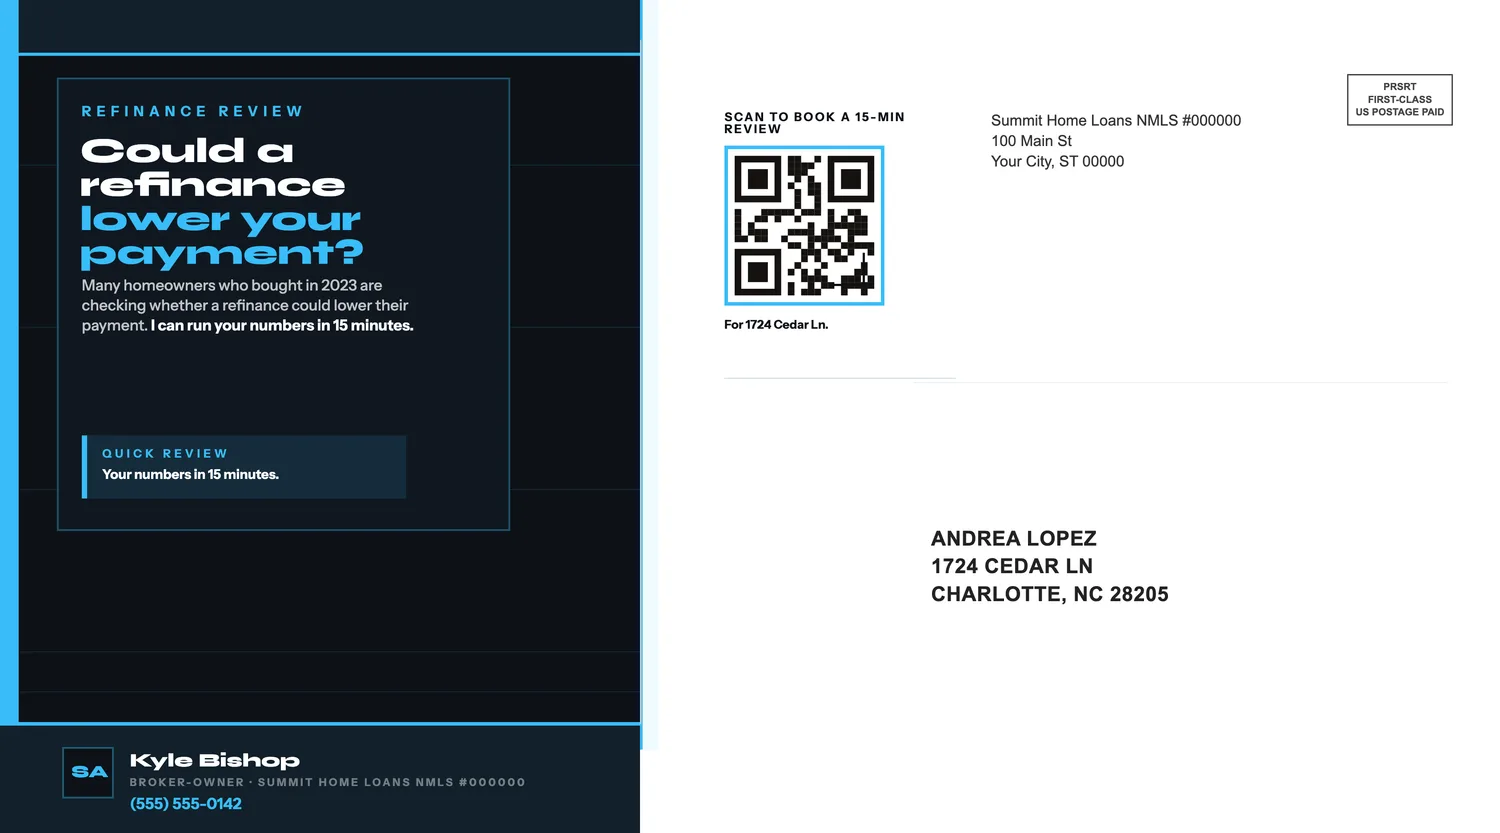
AI-written for this owner · Mailed in 2 days
Loan datefilters for high-rate years
Beforethe trigger leads and rate-shopping start
Reviewedcopy your compliance team approves once
The problem
By the time they're shopping, you're one of ten calls.
Generic "rates have dropped" mailers are everywhere, and many look like official notices, which erodes trust.
Rate-focused copy needs careful disclosures. Without approved templates, every campaign stalls in review.
How it works
From list to mailbox in one workflow.
Five steps from loan-date data to refinance conversations.
app.usespur.com
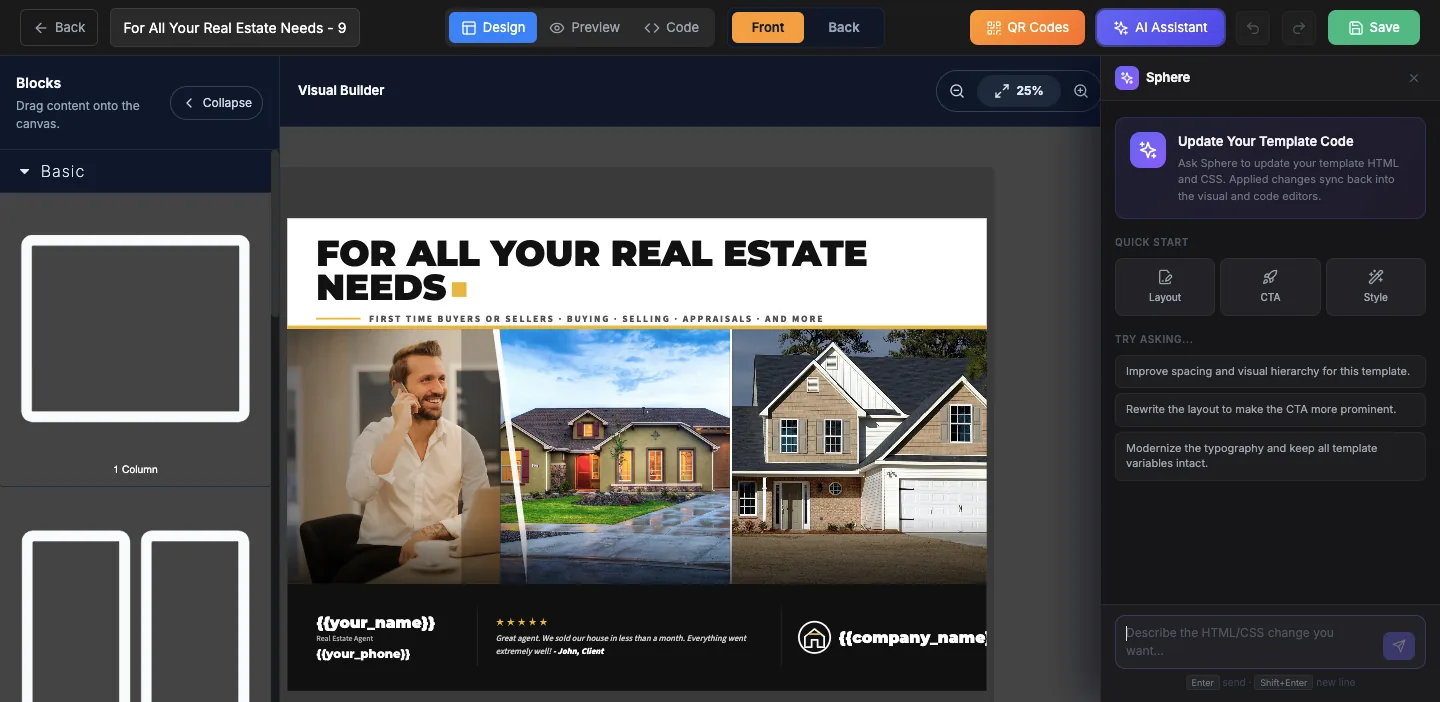
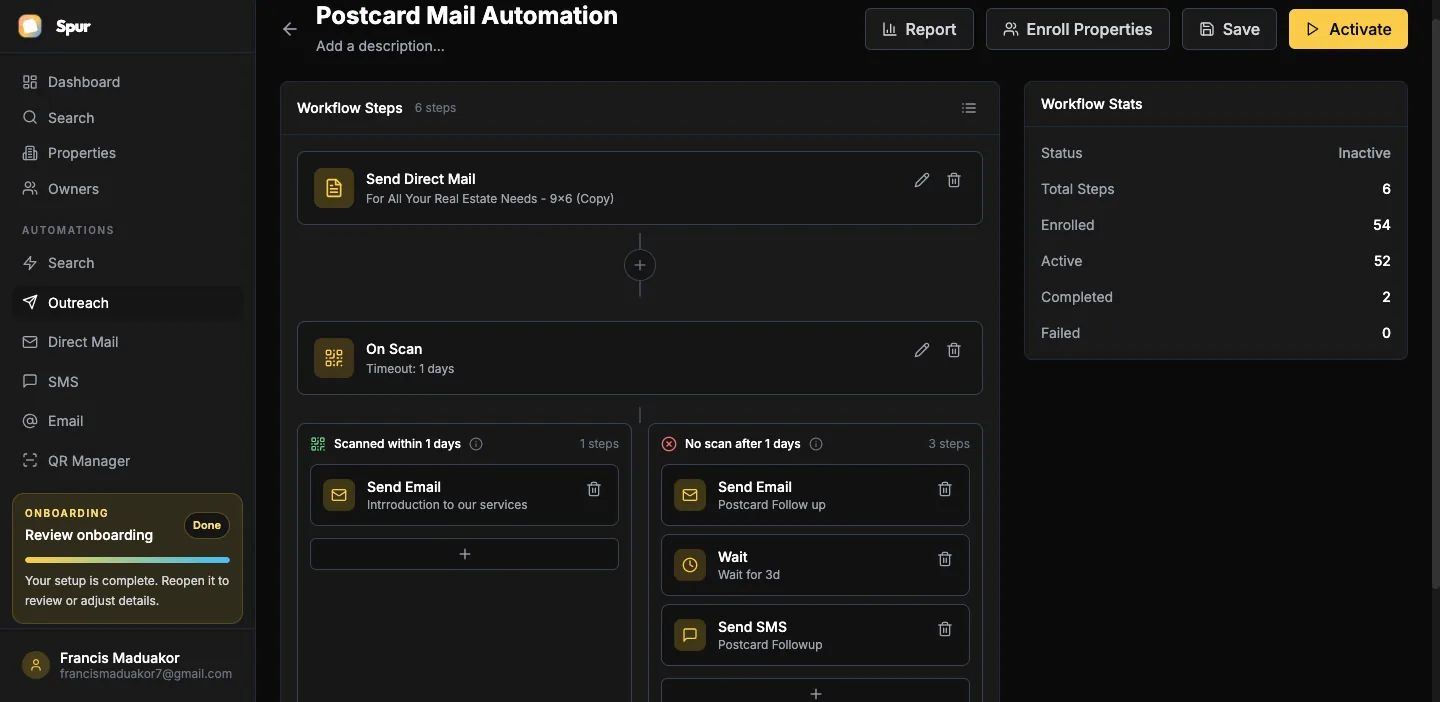
See it in Spur
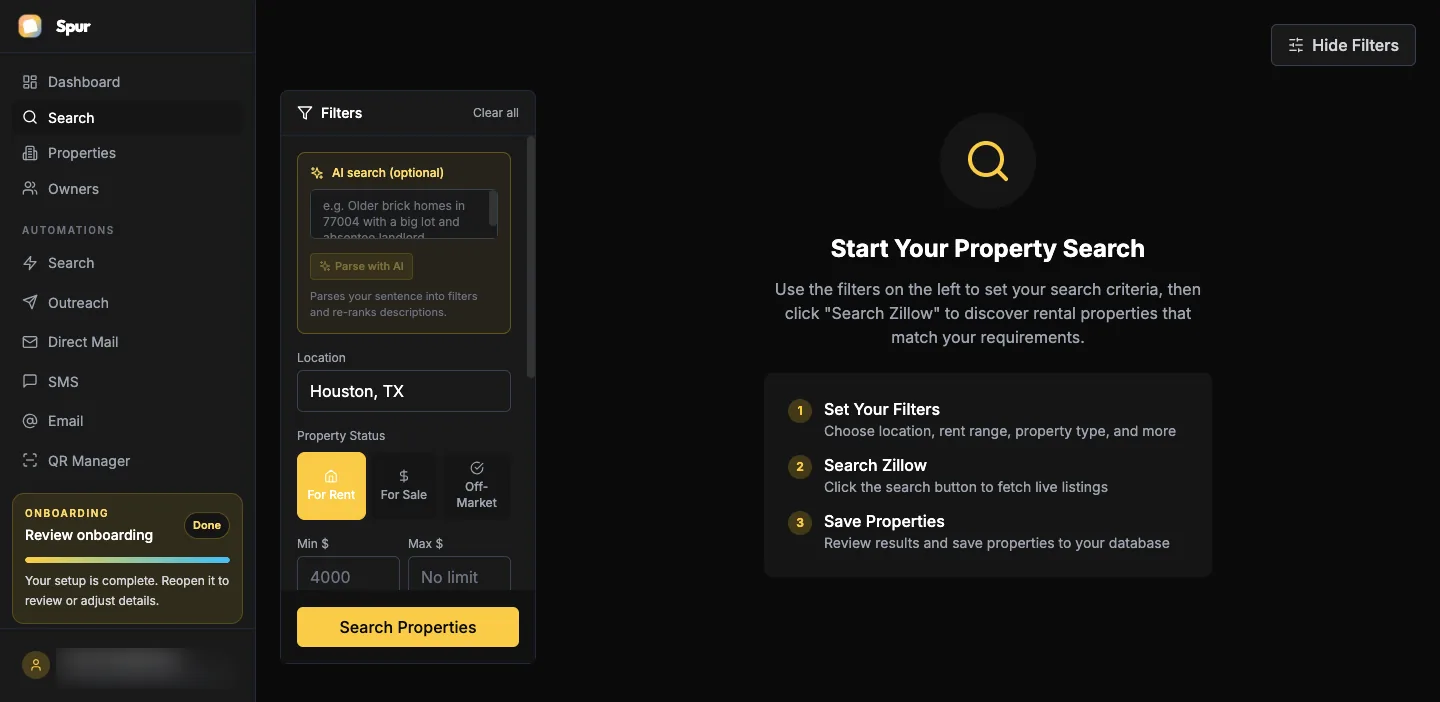
A refinance list in Spur
Sample Charlotte homeowners who bought in 2023–2024. Names are partly masked.
Charlotte, NCOwner-occupiedPurchased 2023–2024Loan $250K+
- Andrea L.1724 Cedar LnPurchased Oct 2023Est. 14% equity$312K loan
- Ben & Mia C.4518 Park RdPurchased Mar 2024Est. 11% equity$408K loan
- Darnell W.820 Woodlawn RdPurchased Aug 2023Est. 18% equity$276K loan
- Sofia R.3109 Selwyn AvePurchased Nov 2023Est. 21% equity$520K loan
- Greg H.2240 Shamrock DrPurchased Jan 2024Est. 9% equity$264K loan
AI draft for Andrea L. · 1724 Cedar Ln
Hi Andrea,
I'm Kyle Bishop, a loan officer with Summit Home Loans here in Charlotte. You bought your home on Cedar Lane in the fall of 2023, when mortgage rates were near their highest in two decades.
Depending on today's rates, your current loan, and your plans, a refinance might lower your monthly payment, shorten your loan term, or neither. The only way to know is to look at your actual numbers, including closing costs and how long you plan to stay.
If you'd like a free, no-obligation 15-minute review, scan the code to pick a time. I'll tell you honestly whether it makes sense.
Kyle Bishop · Summit Home Loans · NMLS #000000 · Equal Housing Lender
Sample data for illustration. Your results depend on your market and filters.
Playbook
How to run refinance direct mail that builds trust
Refinance volume follows rates. When rates fall, homeowners who borrowed at higher rates can lower their payment or term, and lenders compete hard for them. The best time to reach those homeowners is before they apply anywhere. Once they do, their credit inquiry can be sold as a trigger lead, and they hear from many lenders at once.
Build your list from property records. Owners who bought or refinanced in high-rate periods, such as late 2023, when 30-year rates approached 8%, and much of 2024, are the natural audience. Filter by loan amount too; larger balances get more benefit from a rate drop. Keep the list ready so you can mail as soon as the market moves.
Mortgage mail is advertising, and federal rules apply. Stating a rate, payment, or other trigger terms requires specific disclosures, and the Mortgage Acts and Practices Advertising Rule prohibits misleading claims, including implying a government affiliation or that the homeowner has been pre-approved when they haven't. Include your NMLS ID and Equal Housing language, and have compliance approve your templates.
Honest framing performs well. Rather than promising savings, invite the homeowner to check whether a refinance makes sense for them, considering closing costs and how long they plan to stay. A break-even explanation shows expertise and builds trust.
Avoid look-alike notices. Mailers that mimic official documents or past-due notices may draw opens, but they damage your reputation and can attract regulatory attention. A clear, branded letter from a named loan officer is more effective over time.
Track every scan and booking so you know which segments respond when rates move.
Plan your capacity before you mail. When rates fall, refinance demand rises quickly across the market. Mail your segments in waves you can handle, so every homeowner who scans gets a prompt, accurate review rather than a slow callback.
6×return on a year of Spur Team from one $350,000 loan
One refinance covers a year of Spur several times.
- Spur Team: $588/yr billed annually
- 600 homeowners × 2 postcards = 1,200 at $1.09 = $1,308
- One $350,000 refinance at 100 bps compensation = $3,500, about 6× your subscription
Example math. Compensation structures vary by lender and channel. Run your own numbers →
One tool, not four
Spur vs. the usual refinance marketing
What you needThe usual waySpur
Homeowners by loan and purchase dateTrigger leads shared with many lenders✓ Built in
Contact info for follow-upList brokers✓ Built in
Personalized, pre-approved templatesGeneric mass mailers✓ Built in
Booking by QR with instant alertsInbound calls only✓ Built in
Ready-to-mail segments when rates moveRebuilding lists each time✓ Built in
FAQ
Refinance mail questions
How do I find refinance leads?
Target owner-occupied homes purchased or refinanced when rates were high, such as 2023–2024, filtered by loan amount and equity. Spur builds this list from property records.
Can I put rates on my refinance mailers?
Only with the disclosures federal rules require when you state rates or other trigger terms. Have your compliance team approve any rate-focused copy.
How is this different from trigger leads?
Trigger leads come from credit inquiries after a homeowner applies, and are sold to many lenders. Spur reaches homeowners from property data before they start shopping.
What should a refinance letter say?
Reference their home and purchase year, explain that a refinance may or may not make sense, and invite a free review. Include your NMLS ID and Equal Housing language.
When should I mail refinance candidates?
As soon as rates move meaningfully below what your segment borrowed at. Keep the list built so you can mail within days.
Keep exploring
Related plays and guides
Start in minutes. No card required.
Be the first loan officer they hear from.
Build your refinance segments now, get your templates approved, and mail the day rates move.
Build my refinance list — freeFree forever plan · No card · 20 property searches a month
Prefer a walkthrough? Book a demo