Mailing everyone with equity wastes postage on owners who'd never give up a 3% mortgage.
Lender play · Cash-out refinance
Cash-out refinance prospecting: find the owners for whom it actually makes sense.
Cash-out refinancing fits a specific homeowner: lots of equity and either a higher-rate mortgage or none at all. Spur finds those owners by equity, loan date, and ownership length, and mails a compliance-reviewed letter that invites them to see whether a cash-out makes sense for their goals.
Free forever plan · No card · 20 property searches a month
USPSFirst-Class
Sarah Ellis640 S Gilpin StDenver, CO 80209Scan to book a 15-min review
Sarah E. booked an equity review · 20 min ago
AI-written for this owner · Mailed in 2 days
50%+equity and loan-date filters
No loanand higher-rate owners, not low-rate ones
Bookedreviews by QR, straight to your calendar
The problem
Most cash-out mail goes to the wrong owners.
Turning unsecured debt into mortgage debt is a serious decision. Pushy copy creates complaints, not loans.
Owners don't know their equity. Without a clear, friendly invitation to check, they never start.
How it works
From list to mailbox in one workflow.
Five steps from equity data to cash-out conversations.
app.usespur.com
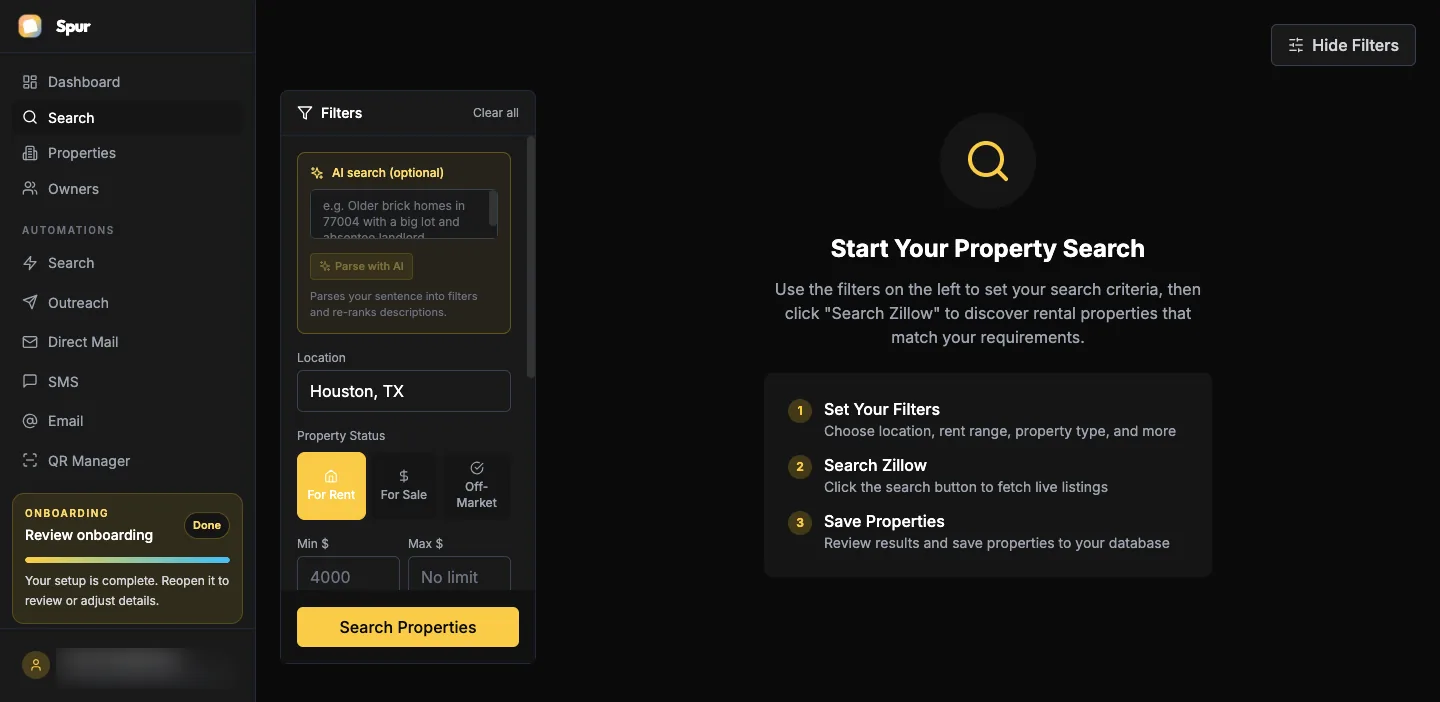
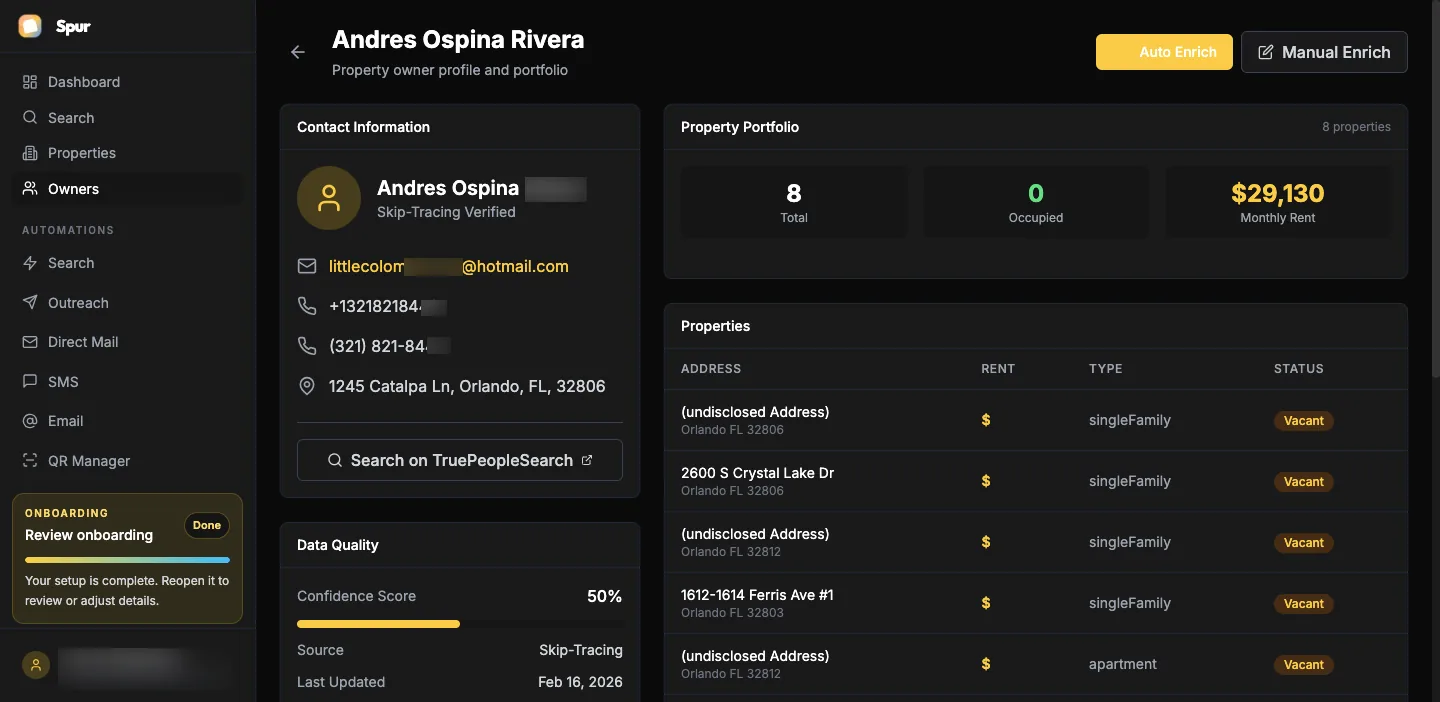
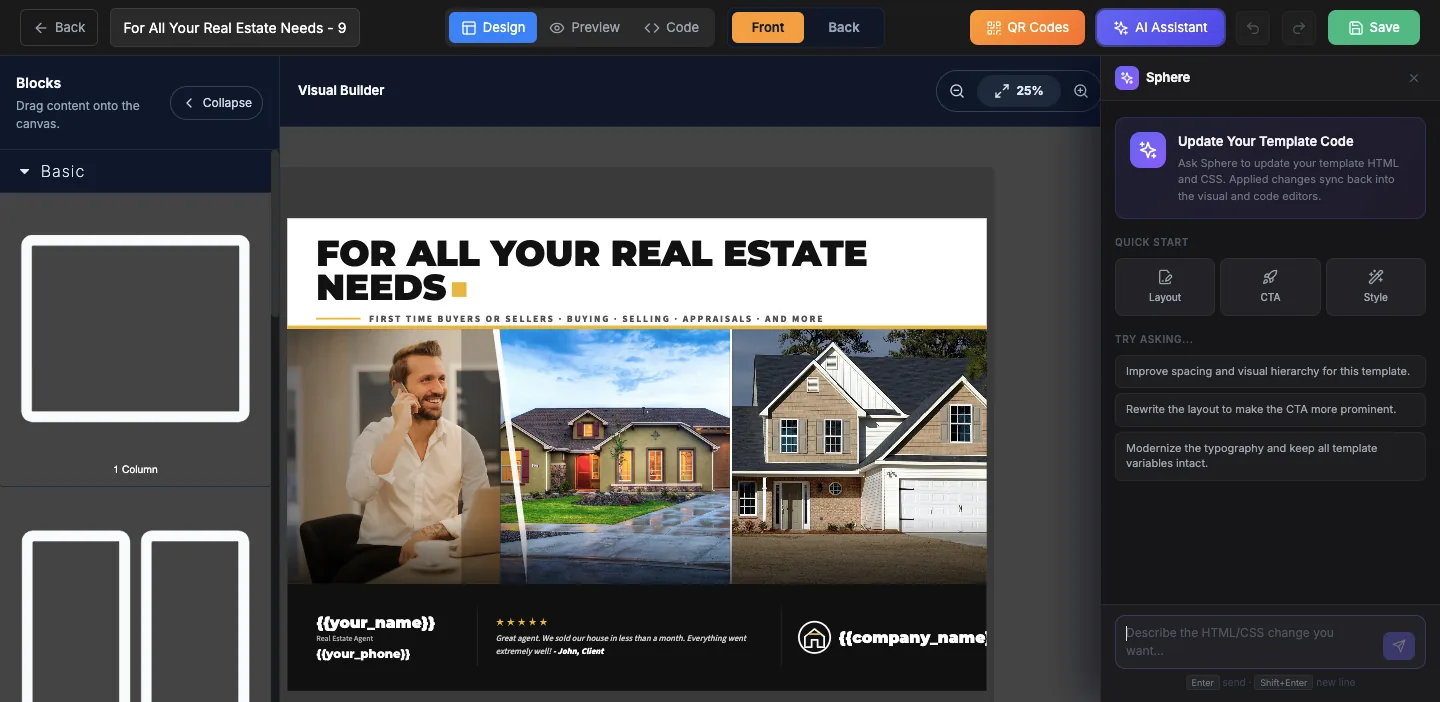
See it in Spur
A cash-out list in Spur
Sample Denver homeowners with high equity and no mortgage or a higher-rate loan. Names are partly masked.
Denver 80209, 80210Owner-occupiedEquity 50%+No loan or loan 2023–24
- Sarah E.640 S Gilpin StPurchased 2014 · refi 2023Est. 58% equity
- Yolanda R.455 S Franklin StPurchased 1998No mortgageOwned 28 yrs
- Mark & Dana P.1120 S Vine StPurchased 2011 · HELOC 2024Est. 63% equity
- Ken & Alice W.780 S Race StPurchased 2009No mortgageEst. 100% equity
- Brian T.903 E Ohio AvePurchased 2016 · refi 2024Est. 51% equity
AI draft for Sarah E. · 640 S Gilpin St
Hi Sarah,
Homes in Washington Park have appreciated significantly since you bought on South Gilpin in 2014, so you may have more equity than you realize.
Homeowners in your position sometimes use a cash-out refinance to renovate, fund a large expense, or replace higher-interest debt with a single payment. It isn't right for everyone. It replaces your current mortgage and uses your home as collateral, so it depends on your rate, your goals, and the costs involved.
If you'd like a no-cost, 15-minute review of your options, scan the code to pick a time. There's no obligation to apply.
James Rivera · Mile High Lending · NMLS #000000 · Equal Housing Lender
Sample data for illustration. Your results depend on your market and filters.
Playbook
Who a cash-out refinance is right for
A cash-out refinance replaces a homeowner's existing mortgage with a larger one and pays out the difference in cash. It's a good fit for owners with substantial equity who either have no mortgage or have a rate close to, or higher than, current rates. For owners with a much lower first-mortgage rate, a home equity line is usually the better product, which is why targeting matters.
Build your list from that logic. Start with owner-occupied homes with 50% or more estimated equity. Then include owners with no recorded mortgage and owners whose current loan came from a higher-rate period, and exclude owners who locked in very low rates. Long-time owners in appreciating neighborhoods often have the most equity.
Most conventional cash-out refinances cap the new loan at about 80% of the home's value, so owners need meaningful equity to come away with cash. Explaining that range helps owners judge whether it's worth a conversation.
Be careful with debt consolidation. Replacing credit card debt with mortgage debt can lower monthly payments, but it secures that debt with the home and can extend repayment for decades. Describe it accurately and avoid framing equity as free money. Regulators watch for misleading claims in mortgage ads, including false promises of savings and implied government affiliation.
Follow the usual mortgage advertising rules: include your NMLS ID and Equal Housing language, avoid stating rates or payments without required disclosures, and have compliance approve templates before you scale.
A calm, educational follow-up works better than urgency. Owners considering a cash-out are making a major financial decision, and the lender who explains it clearly is often the one they choose.
Prepare for appraisal questions. Equity estimates from property data are a starting point, not a promise, and the final loan amount depends on an appraisal. Setting that expectation early avoids disappointment and builds credibility when the numbers come in close to your estimate.
6×return on a year of Spur Team from one $350,000 loan
One cash-out loan covers a year of mail.
- Spur Team: $588/yr billed annually
- 500 high-equity owners × 2 postcards = 1,000 at $1.09 = $1,090
- One $350,000 cash-out refinance at 100 bps compensation = $3,500, about 6× your subscription
Example math. Compensation structures vary by lender and channel. Run your own numbers →
One tool, not four
Spur vs. the usual cash-out marketing
What you needThe usual waySpur
Equity plus loan-date targetingMailing every homeowner with equity✓ Built in
Contact info for follow-upList brokers✓ Built in
Personalized, approved copyGeneric "cash out now" mailers✓ Built in
QR booking with instant alertsInbound calls only✓ Built in
Educational follow-upPushy repeat mailers✓ Built in
From Lenders using Spur
Results from the mailbox.
“I targeted high-equity homeowners in three zip codes with AI postcards about cash-out refi options. Got 14 inbound inquiries in the first month. Closed 3 loans.”
FAQ
Cash-out refinance questions
Who should I target for cash-out refinance?
Owner-occupied homeowners with 50%+ equity who have no mortgage or a rate close to or above current rates. Owners with very low rates are usually better served by a HELOC.
How much can homeowners take out?
Most conventional cash-out refinances allow a new loan up to about 80% of the home's value, minus the existing balance. Programs vary.
Can I market cash-out for debt consolidation?
Yes, if it's accurate and not misleading. Explain that the debt becomes secured by the home, and have compliance approve the copy.
What should be on a cash-out mailer?
Your NMLS ID, Equal Housing language, and no rates or payments unless you include the required disclosures. Invite a review rather than promising savings.
How is cash-out different from a HELOC?
A cash-out refinance replaces the existing mortgage with a new, larger loan. A HELOC is a separate line of credit that leaves the first mortgage in place.
Keep exploring
Related plays and guides
Start in minutes. No card required.
Reach the owners a cash-out is built for.
Build a targeted equity list, get your template approved, and book your first equity reviews this month.
Build my cash-out list — freeFree forever plan · No card · 20 property searches a month
Prefer a walkthrough? Book a demo