Owners with a low first-mortgage rate won't replace it. Cash-out refinance offers miss them completely.
Lender play · HELOC
HELOC marketing for owners who'd never give up their low first-mortgage rate.
Millions of homeowners have a low first-mortgage rate and lots of equity. They won't refinance, but many still want to renovate or pay for a big expense. Spur finds them, and mails a compliance-reviewed letter that explains how a home equity line could work alongside the loan they want to keep.
Free forever plan · No card · 20 property searches a month
USPSFirst-Class
Robert & Joan Hale4410 Juniper AveMinneapolis, MN 55410Scan to book a 15-min review
Joan H. booked a HELOC review · 3 hrs ago
AI-written for this owner · Mailed in 2 days
Equityfilters by estimated percentage and amount
2020–21first mortgages owners want to keep
Projectsmessaging tied to their home
The problem
Homeowners have equity but won't touch their mortgage.
"Tap your equity" postcards don't explain how a HELOC works next to an existing loan, so owners don't act.
Most owners assume their current bank is the only option. Without outreach, you never get the chance.
How it works
From list to mailbox in one workflow.
Five steps from equity data to HELOC conversations.
app.usespur.com
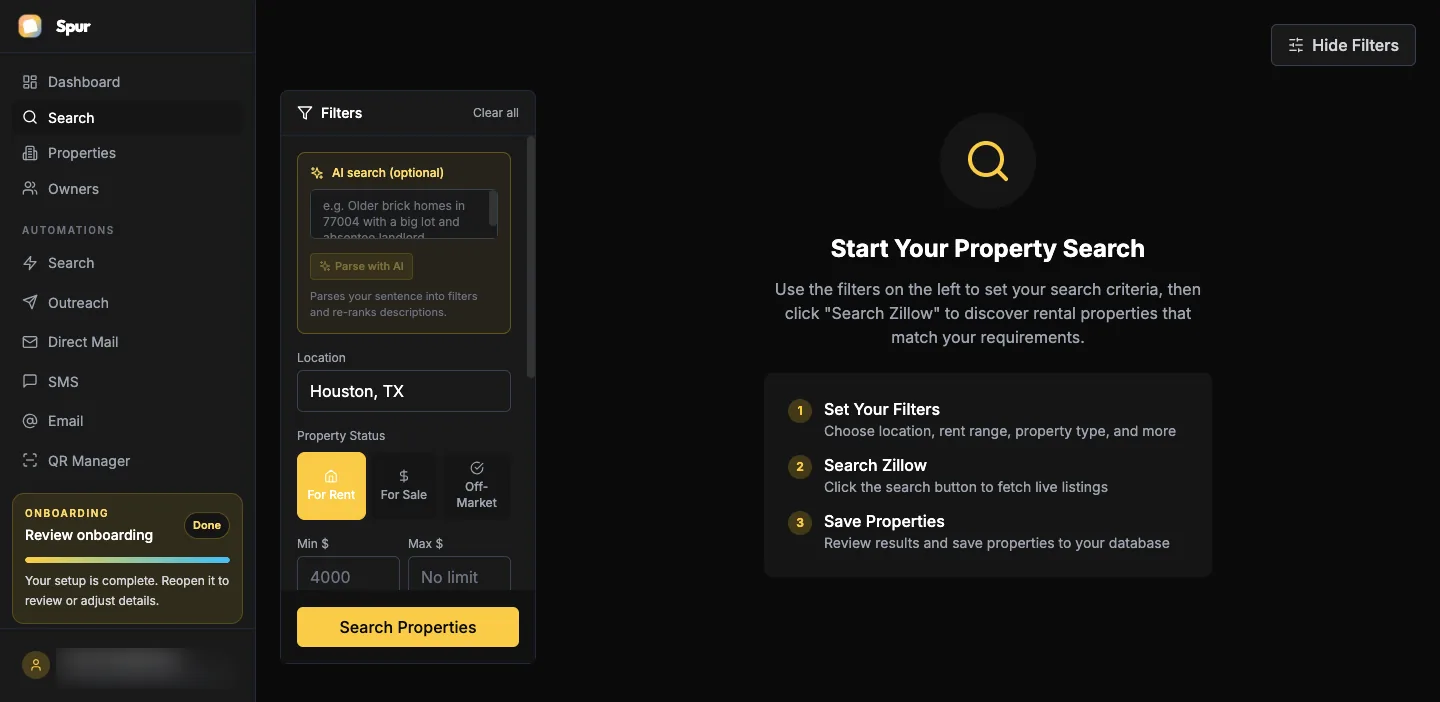
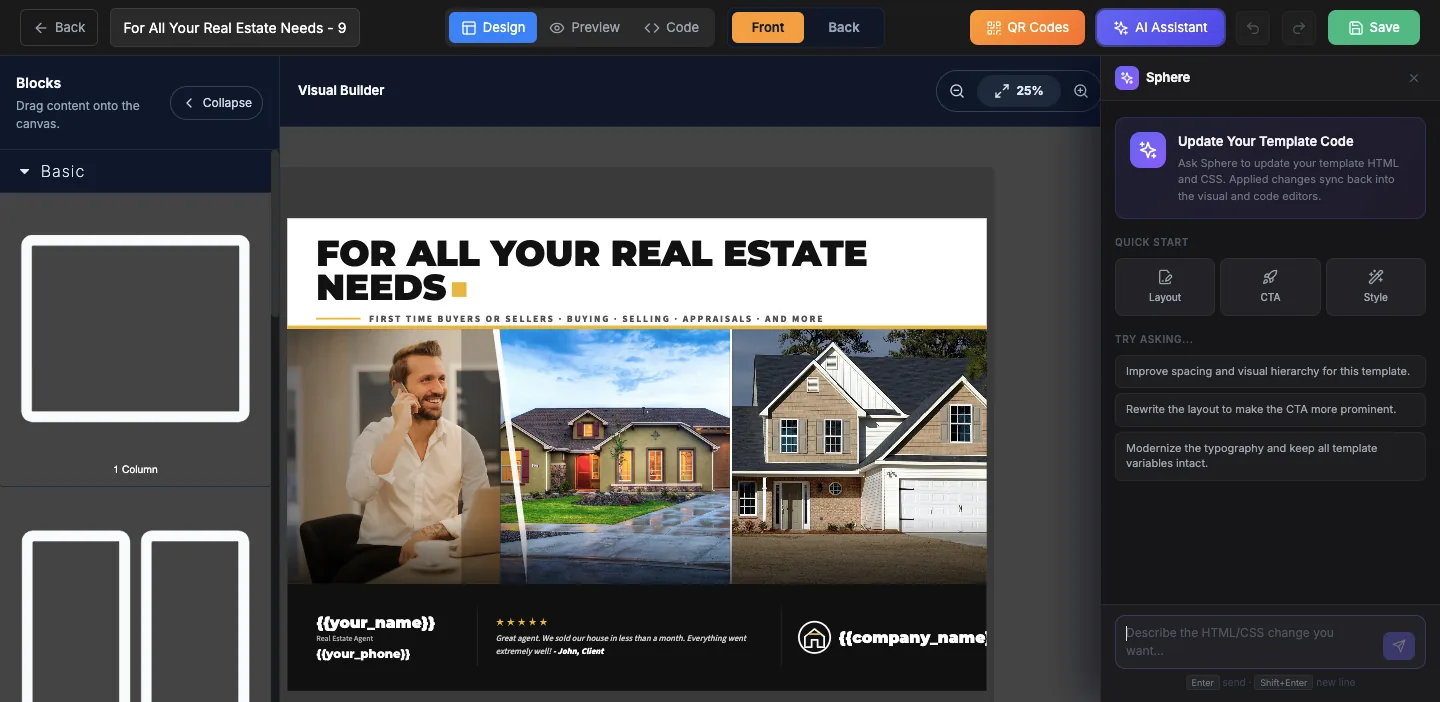
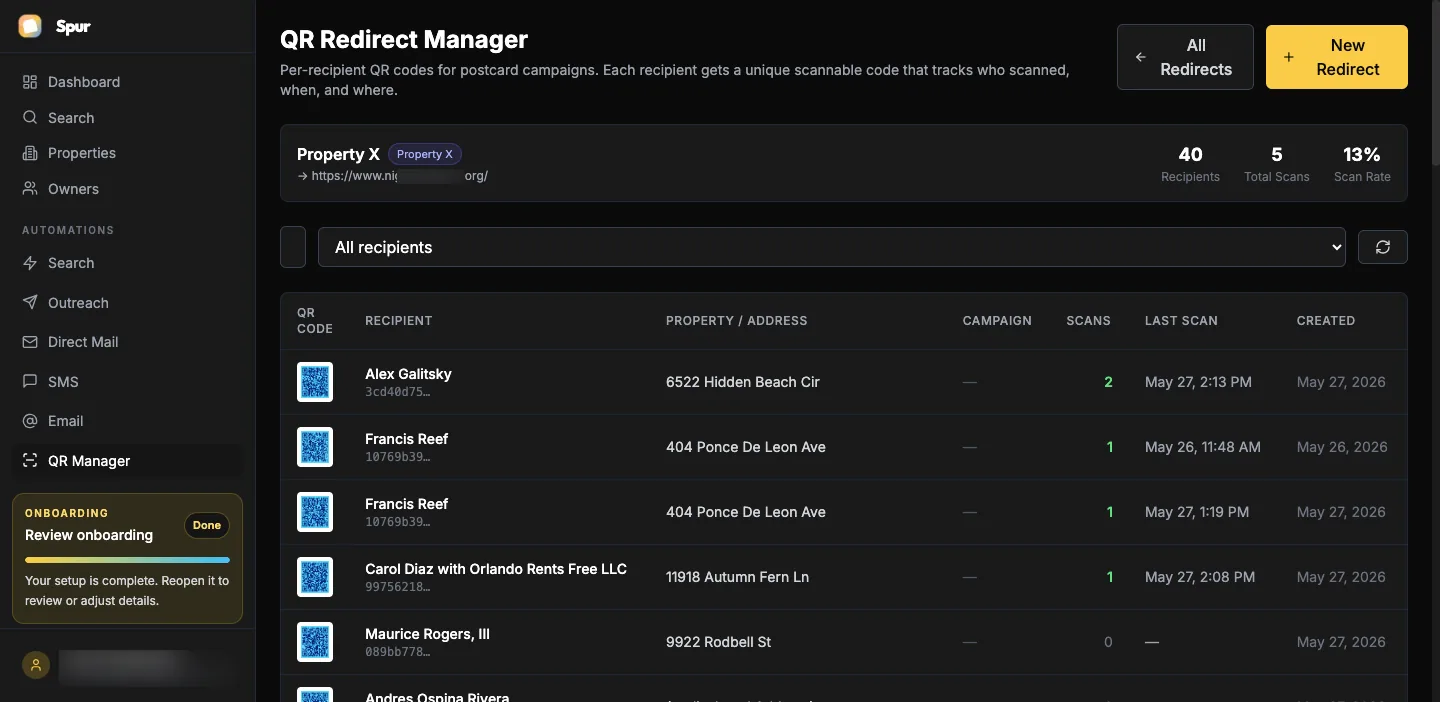
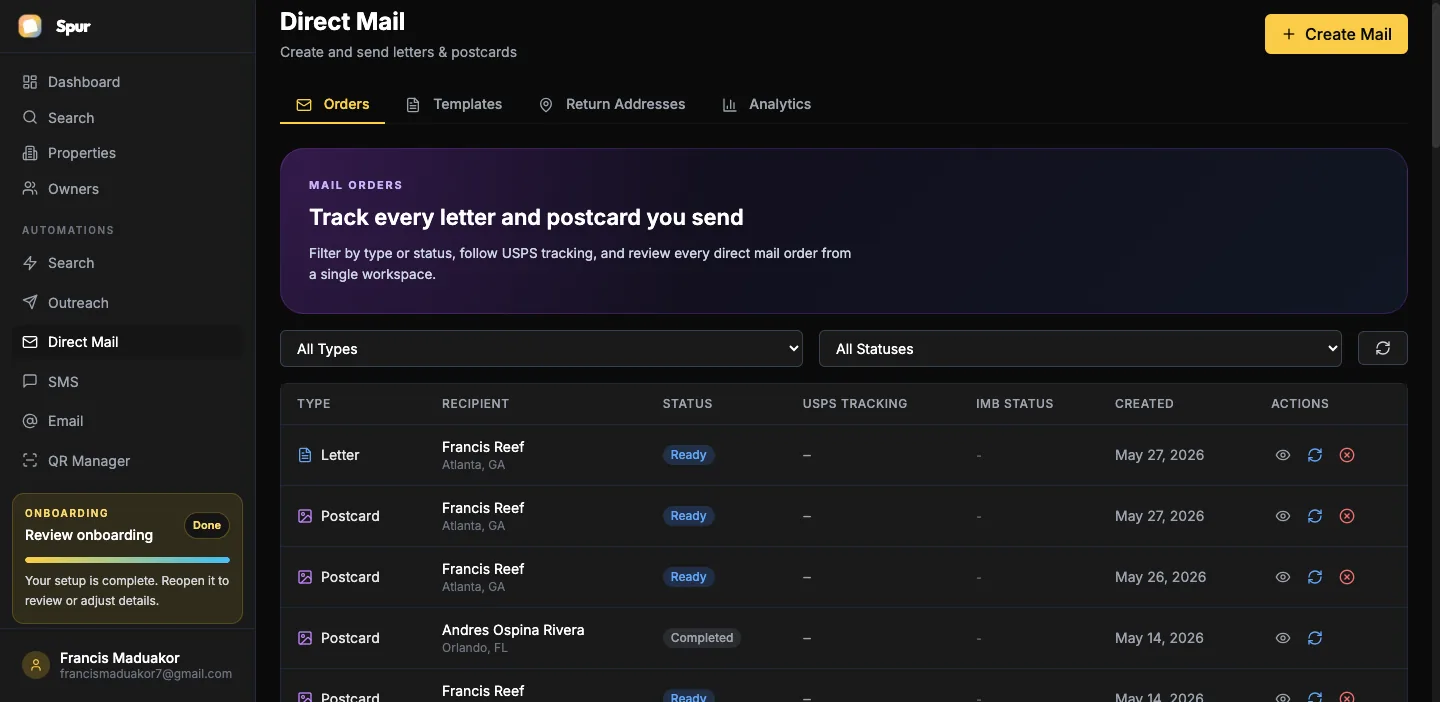
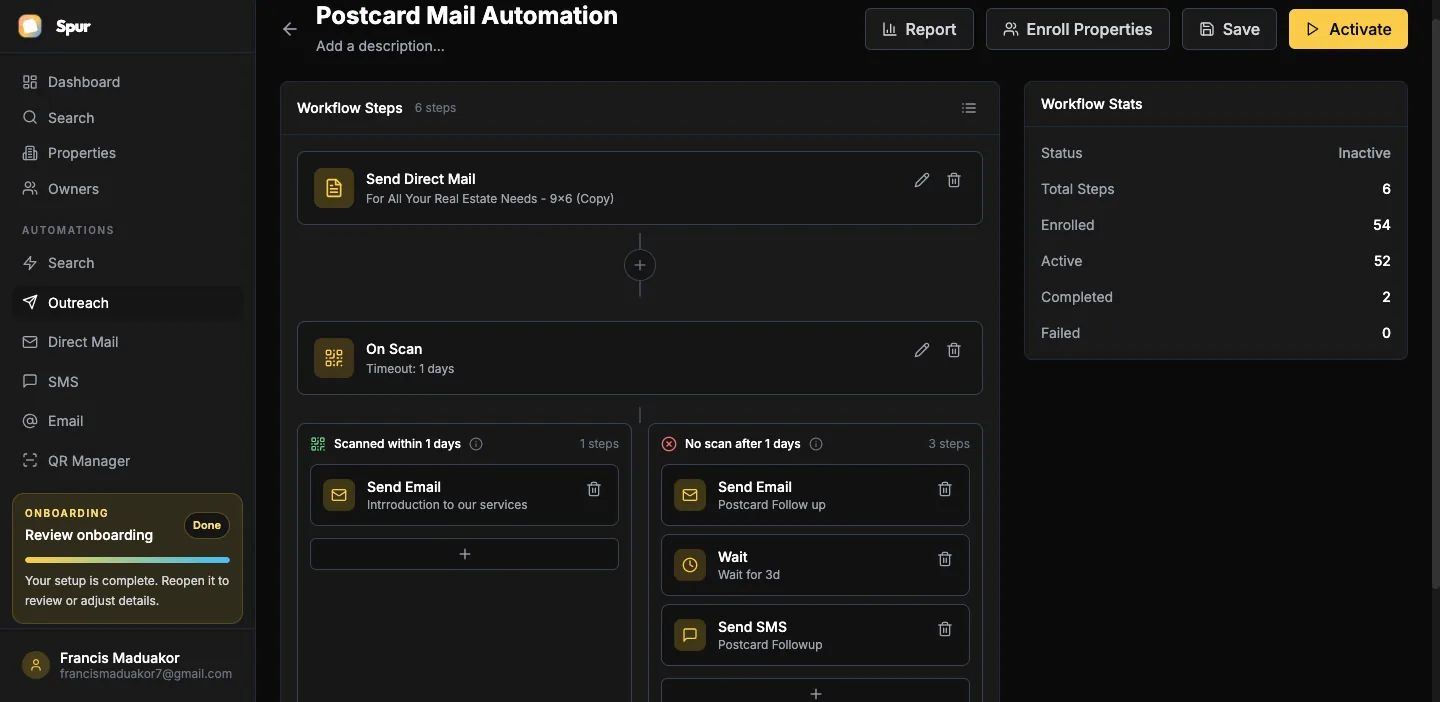
See it in Spur
A HELOC list in Spur
Sample Minneapolis homeowners with high equity and a first mortgage from 2020–2021. Names are partly masked.
Minneapolis, MNOwner-occupiedEquity 40%+First mortgage 2020–21
- Robert & Joan H.4410 Juniper AveMortgage 2021Est. 52% equityBuilt 1938
- Alex P.3522 Girard Ave SMortgage 2020Est. 47% equityOwned 12 yrs
- Tanya & Lou M.5108 Xerxes Ave SMortgage 2021Est. 61% equityBuilt 1950
- Will S.2915 E 50th StMortgage 2020Est. 44% equityOwned 9 yrs
- Hannah K.4021 Abbott Ave SMortgage 2021Est. 58% equityOwned 15 yrs
AI draft for Robert & Joan H. · 4410 Juniper Ave
Dear Robert and Joan,
I'm Nina Clark, a lender with Lakeside Credit Union. Homes on your stretch of Juniper Avenue have gained significant value in recent years, and many owners are using that equity for kitchen updates, additions, and other projects.
If you have a low rate on your current mortgage, you may not want to refinance it. A home equity line of credit works alongside your existing loan, so you can borrow for a project while keeping your first mortgage as it is. Whether it's the right fit depends on your goals and finances.
Scan the code to book a free 15-minute review, and I'll walk you through your options and how much you may be able to access.
Nina Clark · Lakeside Credit Union · NMLS #000000 · Equal Housing Lender
Sample data for illustration. Your results depend on your market and filters.
Playbook
How to market HELOCs to the right homeowners
A home equity line of credit lets homeowners borrow against their equity as needed, usually with a variable rate, while keeping their first mortgage in place. That makes HELOCs especially relevant today. Many homeowners locked in very low first-mortgage rates in 2020 and 2021 and have gained significant equity since, but they don't want to give up their rate with a cash-out refinance.
Build your list around that situation. Filter for owner-occupied homes with substantial estimated equity, often 40% or more, and a first mortgage recorded during low-rate years. Older homes and long-time owners are more likely to have renovation plans; homes in appreciating neighborhoods often have the most equity.
Focus the message on purpose and flexibility. Common uses include renovations, education costs, and consolidating higher-rate debt. Explain plainly how a line works alongside an existing loan. Many owners don't realize they can keep their first mortgage.
HELOC advertising has its own rules. Under Regulation Z, if an ad states certain terms, such as a payment or a rate, it must include specific disclosures, including that rates are variable when they are. Include your NMLS ID and Equal Housing language, and avoid language suggesting the homeowner is already approved. Have compliance approve a template you can personalize at scale.
Be responsible with debt consolidation messages. A HELOC secures debt with the home, so explain that clearly and avoid framing it as free money.
Time your campaigns to project season. Homeowners plan renovations in late winter for spring and in late summer for fall projects. Partnering with local remodelers can also bring warm referrals.
Make the review easy. Many homeowners don't know their equity or how much they could access. Offering a quick, no-obligation estimate based on their home's value and current balance turns a vague interest into a concrete next step, and gives you a natural reason to follow up.
5×return on a year of Spur Team from two $150,000 lines
A few HELOCs cover a year of outreach.
- Spur Team: $588/yr billed annually
- 800 high-equity owners × 2 postcards = 1,600 at $1.09 = $1,744
- Two $150,000 HELOCs at 100 bps compensation = $3,000, about 5× your subscription, plus long-term borrower relationships
Example math. HELOC compensation and economics vary widely by lender. Run your own numbers →
One tool, not four
Spur vs. the usual home equity marketing
What you needThe usual waySpur
Equity and first-mortgage-date filtersBroad list purchases✓ Built in
Property-specific, approved copyGeneric "tap your equity" mailers✓ Built in
QR booking with instant alertsCall-in only✓ Built in
Delivery trackingNone✓ Built in
Seasonal re-mailingManual reorders✓ Built in
FAQ
HELOC marketing questions
Who are the best HELOC prospects?
Owner-occupied homeowners with substantial equity and a low-rate first mortgage they want to keep, especially owners of older homes likely to renovate.
How do I find homeowners with a lot of equity?
Filter by estimated equity, ownership length, and first-mortgage recording date in Spur, then narrow by neighborhood and property age.
What disclosures do HELOC mailers need?
If you state certain terms like a rate or payment, Regulation Z requires specific disclosures. Include your NMLS ID and Equal Housing language, and have compliance approve templates.
HELOC or cash-out refinance: which should I offer?
For owners with a low first-mortgage rate, a HELOC usually makes more sense because they keep their existing loan. Cash-out fits owners with higher rates or no mortgage.
When should I send HELOC mail?
Before renovation seasons: late winter for spring projects and late summer for fall projects.
Keep exploring
Related plays and guides
Start in minutes. No card required.
Reach the owners sitting on equity and a great rate.
Build your HELOC list, get your template approved, and mail before project season.
Build my HELOC list — freeFree forever plan · No card · 20 property searches a month
Prefer a walkthrough? Book a demo