Ads that implied "free money" or no risk of losing the home led to regulatory action, and many homeowners now distrust the product.
Lender play · Reverse mortgage
Reverse mortgage marketing that educates first and never oversells.
Reverse mortgages can help long-time homeowners stay in their homes, but they're often misunderstood and sometimes misleadingly advertised. Spur helps you reach long-held, high-equity homes with a respectful, compliance-reviewed letter that explains how it works, invites family to the conversation, and books an unhurried review.
Free forever plan · No card · 20 property searches a month
USPSFirst-Class
Manuel & Rosa Duarte2810 Fern StSan Diego, CA 92104Scan for the free guide
Rosa D. downloaded the guide · 2 days ago
AI-written for this owner · Mailed in 2 days
Long-heldhigh-equity homes, not age-based lists
Educationfirst, with costs and alternatives
Familyinvited to every conversation
The problem
Reverse mortgage advertising has a trust problem.
Costs, counseling, occupancy rules, and what happens to heirs all need explaining. A postcard slogan can't do it.
Adult children often join the decision. Mail that ignores them can create conflict instead of conversations.
How it works
From list to mailbox in one workflow.
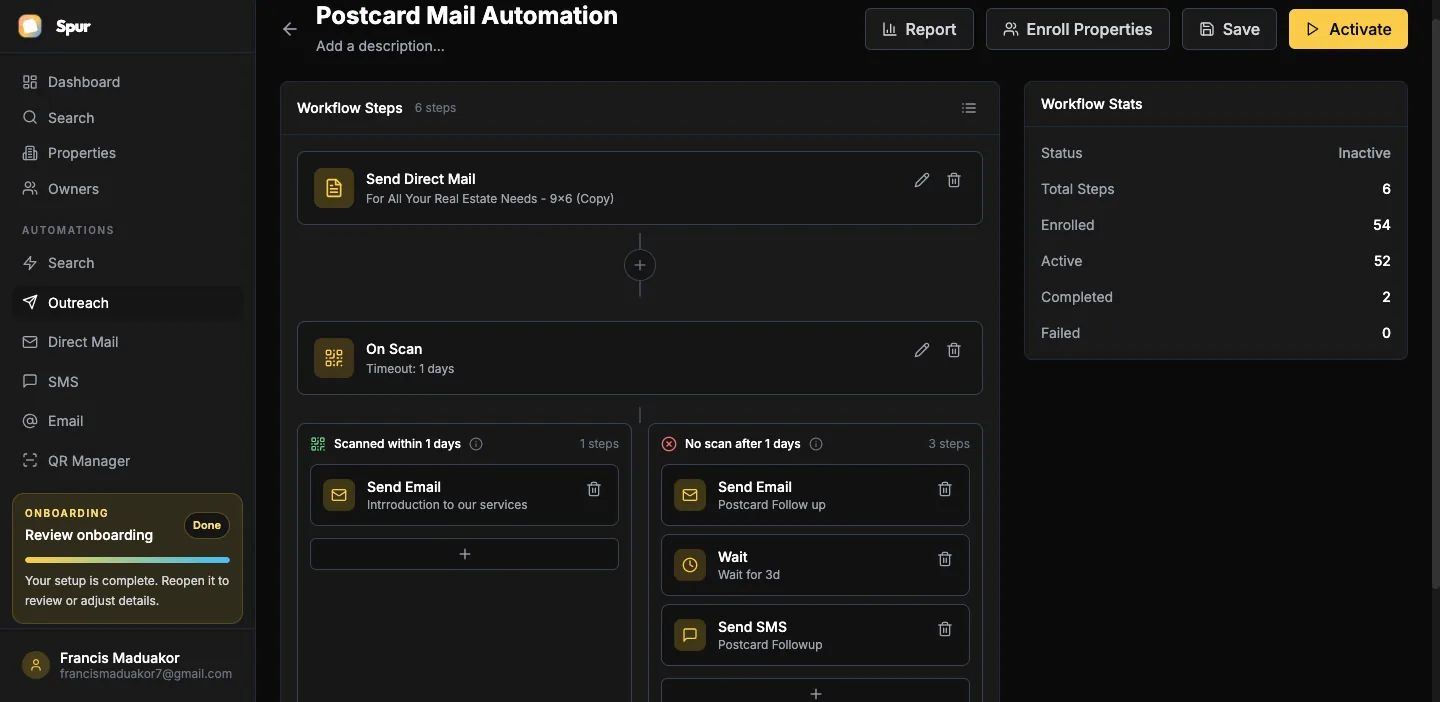
Five steps from long-held homes to informed conversations.
app.usespur.com
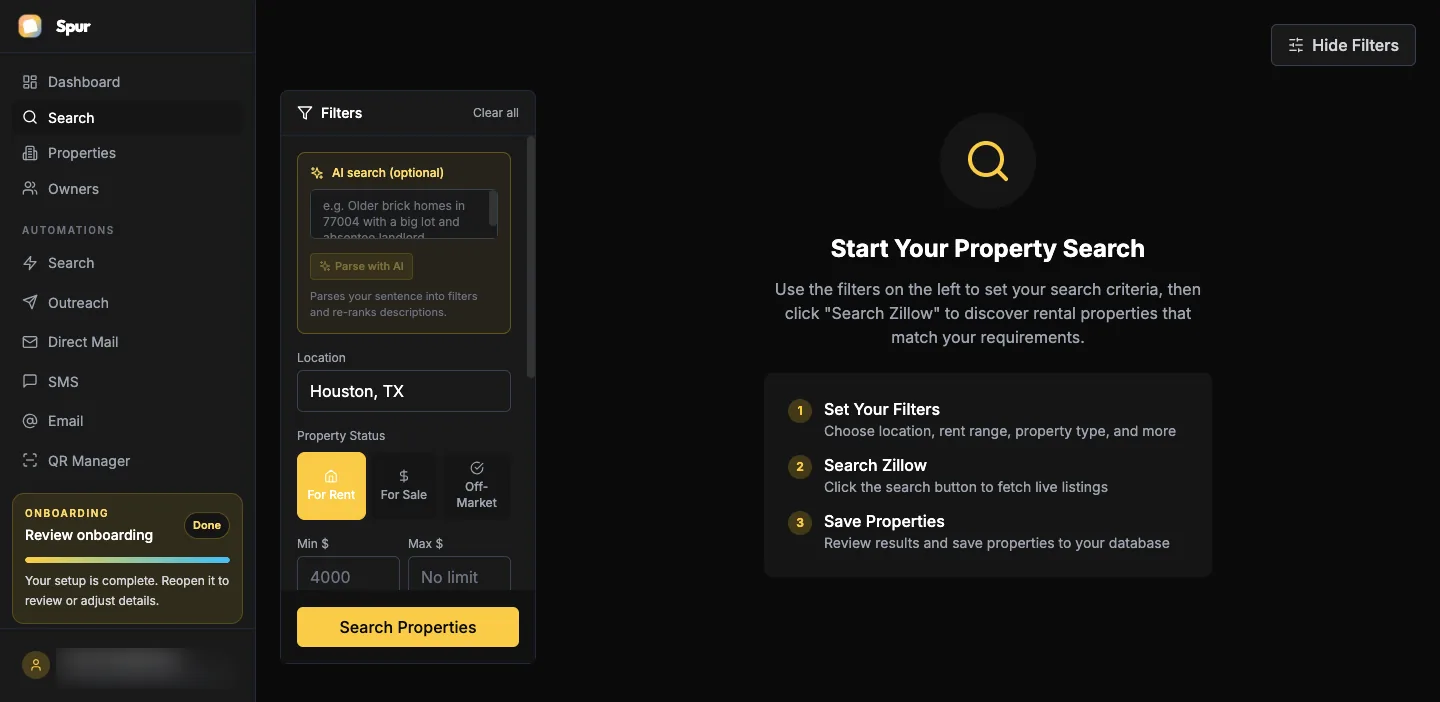
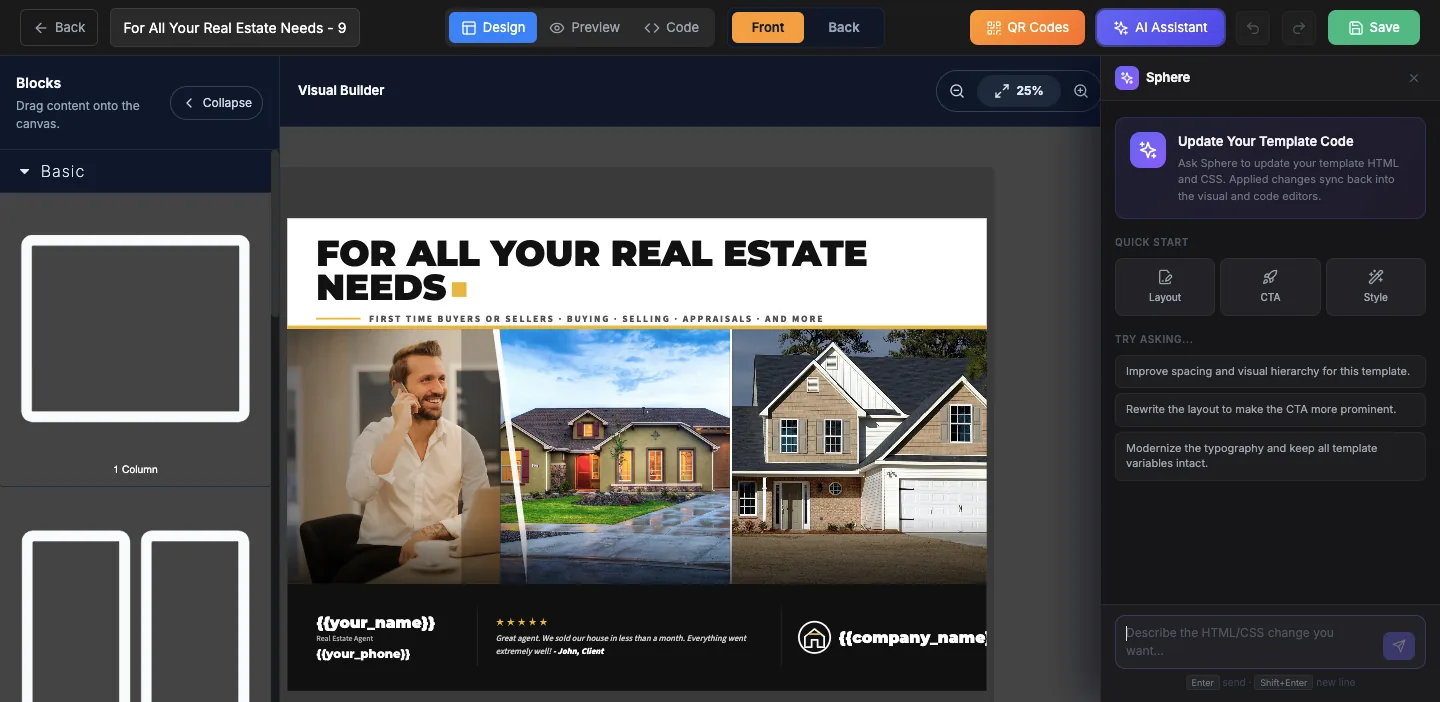
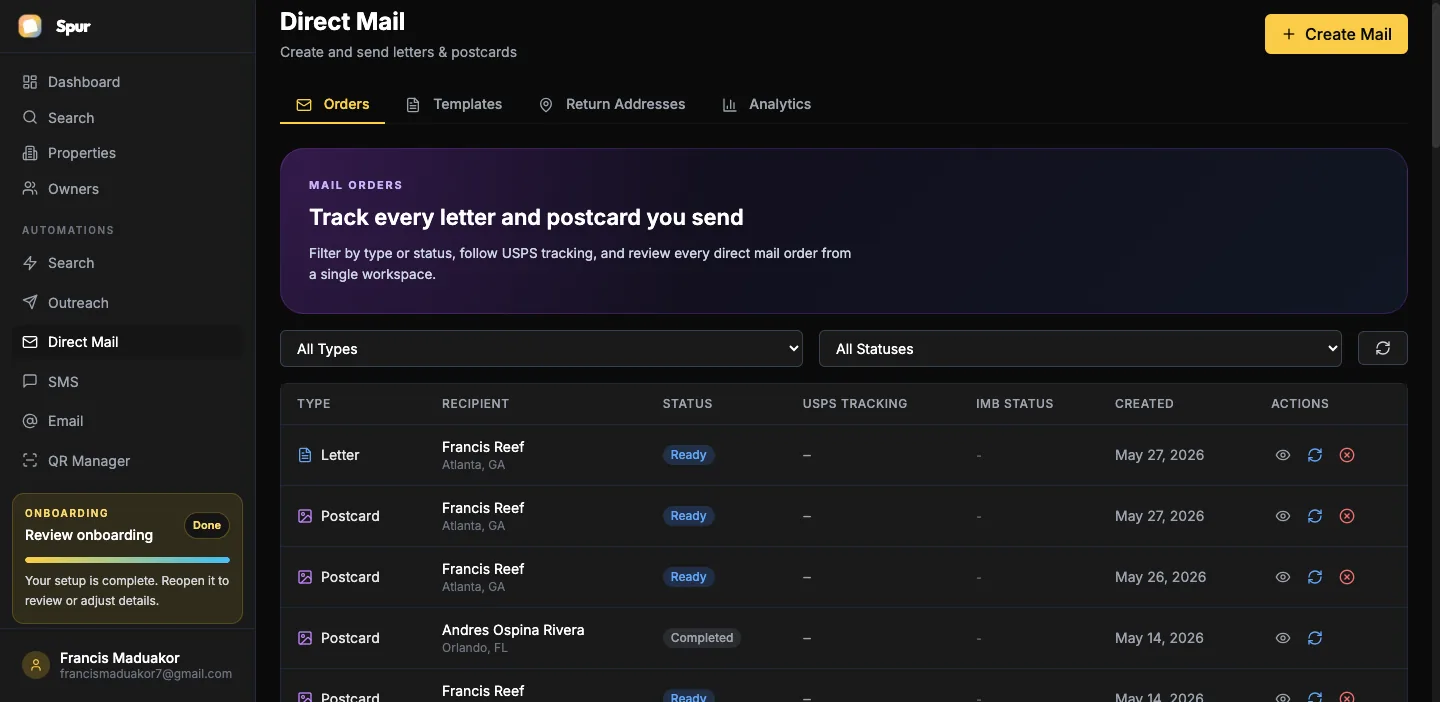
See it in Spur
A reverse mortgage outreach list in Spur
Sample long-held, high-equity homes in San Diego. Names are partly masked.
San Diego, CAOwner-occupiedOwned 20+ yrsEquity 70%+
- Manuel & Rosa D.2810 Fern StOwned 34 yrsNo mortgageEst. 100% equity
- Gloria T.4419 Arizona StOwned 27 yrsEst. 88% equity
- Frank & June L.3650 Pershing AveOwned 41 yrsNo mortgageBuilt 1952
- Harold B.1834 Granada AveOwned 23 yrsEst. 79% equity
- Irene W.3105 Kalmia StOwned 30 yrsNo mortgageEst. 100% equity
AI draft for Manuel & Rosa D. · 2810 Fern St
Dear Manuel and Rosa,
I'm Helen Ward, a reverse mortgage specialist with Sunrise Home Lending in San Diego. You may have seen reverse mortgage ads that seemed too good to be true. I'd like to offer a clear, honest explanation instead.
A reverse mortgage is a loan for homeowners 62 and older that lets you convert part of your home's equity into funds while you continue to live there. You still own the home and must keep paying property taxes, insurance, and upkeep. The loan has costs, it grows over time, and it is repaid when you sell, move out, or pass away. Independent counseling is required before you apply, and it isn't right for everyone.
If you'd like my free plain-English guide, including alternatives, scan the code. Your family is always welcome to join any conversation.
Helen Ward · Sunrise Home Lending · NMLS #000000 · Equal Housing Lender
Sample data for illustration. Your results depend on your market and filters.
Playbook
How to market reverse mortgages responsibly
Most reverse mortgages in the U.S. are Home Equity Conversion Mortgages (HECMs), insured by the Federal Housing Administration. They let homeowners 62 and older convert part of their equity into a lump sum, monthly payments, or a line of credit without making monthly mortgage payments. The loan balance grows over time and is repaid when the borrower sells, moves out, or passes away. Borrowers must live in the home, keep paying taxes, insurance, and maintenance, and complete counseling with a HUD-approved counselor before applying.
Reverse mortgage advertising is closely watched. Regulators have taken action against ads that implied borrowers couldn't lose their home, that the loan was a government benefit, or that it had no costs. The Mortgage Acts and Practices Advertising Rule prohibits these kinds of misrepresentations. Your mail should be educational, accurate about costs and obligations, and approved by compliance.
Build your list from property facts, not assumptions. Long-held homes with high equity and little or no remaining mortgage are the natural audience. Eligibility is confirmed during the application, so don't imply a homeowner qualifies. Be mindful of fair lending rules and work with compliance on how you define your audience.
Write for the whole family. Many older homeowners discuss this decision with adult children, and heirs need to understand what happens to the home later. Inviting family into the conversation builds trust and reduces misunderstandings.
Offer education before a sales call. A plain-English guide that covers costs, obligations, counseling, and alternatives such as downsizing or a HELOC positions you as a trusted advisor.
Follow up gently, with long gaps and an easy way to opt out. Pressure is the fastest way to lose trust with this audience and draw complaints.
Keep careful records of every piece you mail and every conversation. Reverse mortgage complaints often come from family members later, and documentation of clear, balanced information protects both the borrower and your company.
5×return on a year of Spur Team from one funded loan
A few informed borrowers cover the year.
- Spur Team: $588/yr billed annually
- 300 long-held homes × 2 letters = 600 at $1.39 = $834
- One funded reverse mortgage with $3,000 in compensation = 5× your subscription
Example math. Compensation varies by lender; responsible outreach matters more than volume here. Run your own numbers →
One tool, not four
Spur vs. the usual reverse mortgage marketing
What you needThe usual waySpur
Long-held, high-equity home listsPurchased lead lists✓ Built in
Educational, approved lettersSlogan-heavy mailers✓ Built in
Delivery trackingNone✓ Built in
Free guide by QRCall-in only✓ Built in
Gentle, spaced follow-upRepeated hard-sell mail✓ Built in
FAQ
Reverse mortgage marketing questions
How do I market reverse mortgages?
Reach long-held, high-equity homeowners with educational, compliance-approved letters that explain costs and obligations, offer a free guide, and invite family to the conversation.
What can't reverse mortgage ads say?
They can't misrepresent costs, imply there's no risk of losing the home, or suggest a government benefit or affiliation. Have compliance review every template.
Who is eligible for a reverse mortgage?
For a HECM, homeowners 62 and older who live in the home as their primary residence, have sufficient equity, and complete HUD-approved counseling. Eligibility is confirmed in the application.
Should I involve the homeowner's family?
Yes. Inviting adult children or heirs builds trust and helps everyone understand what happens to the home later.
How often should I follow up?
Sparingly. One or two educational follow-ups, weeks apart, with an easy way to opt out.
Keep exploring
Related plays and guides
Start in minutes. No card required.
Be the reverse mortgage lender families trust.
Build a list of long-held, high-equity homes, get your educational letter approved, and mail it this month.
Build my reverse mortgage list — freeFree forever plan · No card · 20 property searches a month
Prefer a walkthrough? Book a demo