Long-time landlords get cash offers below value every week. Few investors offer full price paid over time.
Investor play · Seller finance
Seller finance leads: owners who'd rather be the bank than take a check.
Owners with no mortgage can sell on terms, turning their house into steady monthly income. Spur finds free-and-clear, long-held properties, reaches the owner, and mails a clear offer that explains what seller financing could mean for them.
Free forever plan · No card · 20 property searches a month
USPSFirst-Class
Walter Dalton88 Hillcrest RdAsheville, NC 28804Scan to see the numbers
Walter D. viewed your sample terms · 1 hr ago
AI-written for this owner · Mailed in 2 days
No loanfree-and-clear filter on every list
Monthlyincome offers instead of lowball cash
Trackedletters that land before your call
The problem
Owners who'd love seller financing never hear it offered.
Many owners have never considered carrying a note. A short, clear example of the monthly income does the work.
Seller financing works best without a mortgage. Mailing everyone wastes money on owners who can't do it.
How it works
From list to mailbox in one workflow.
Five steps from a free-and-clear list to a deal on terms.
app.usespur.com
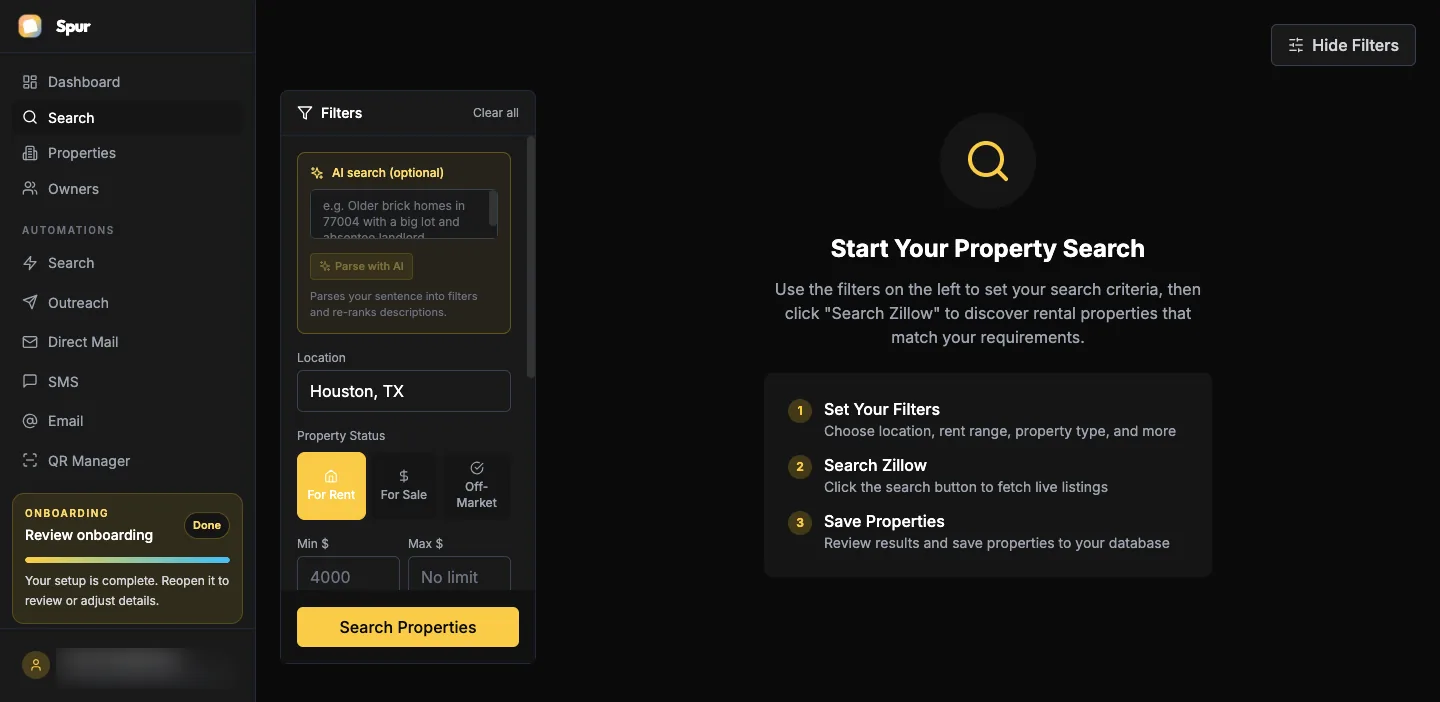
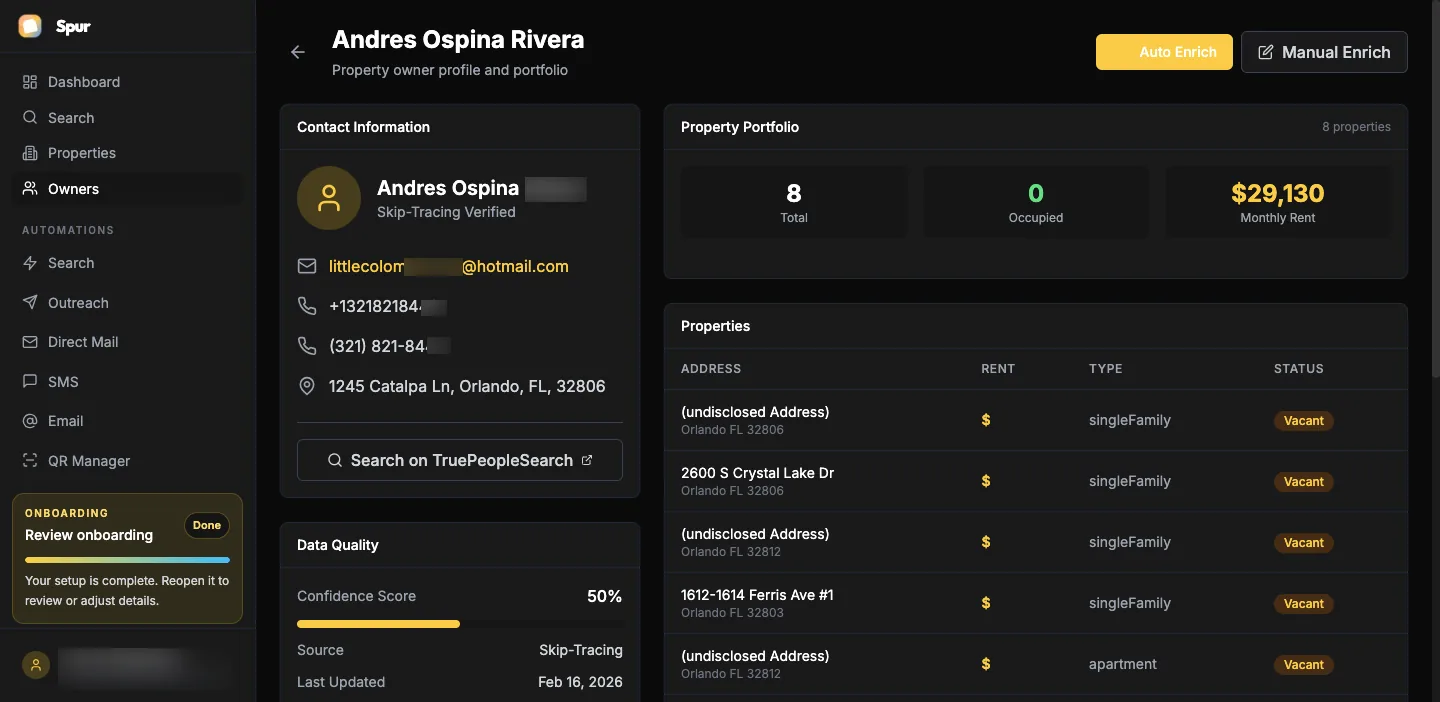
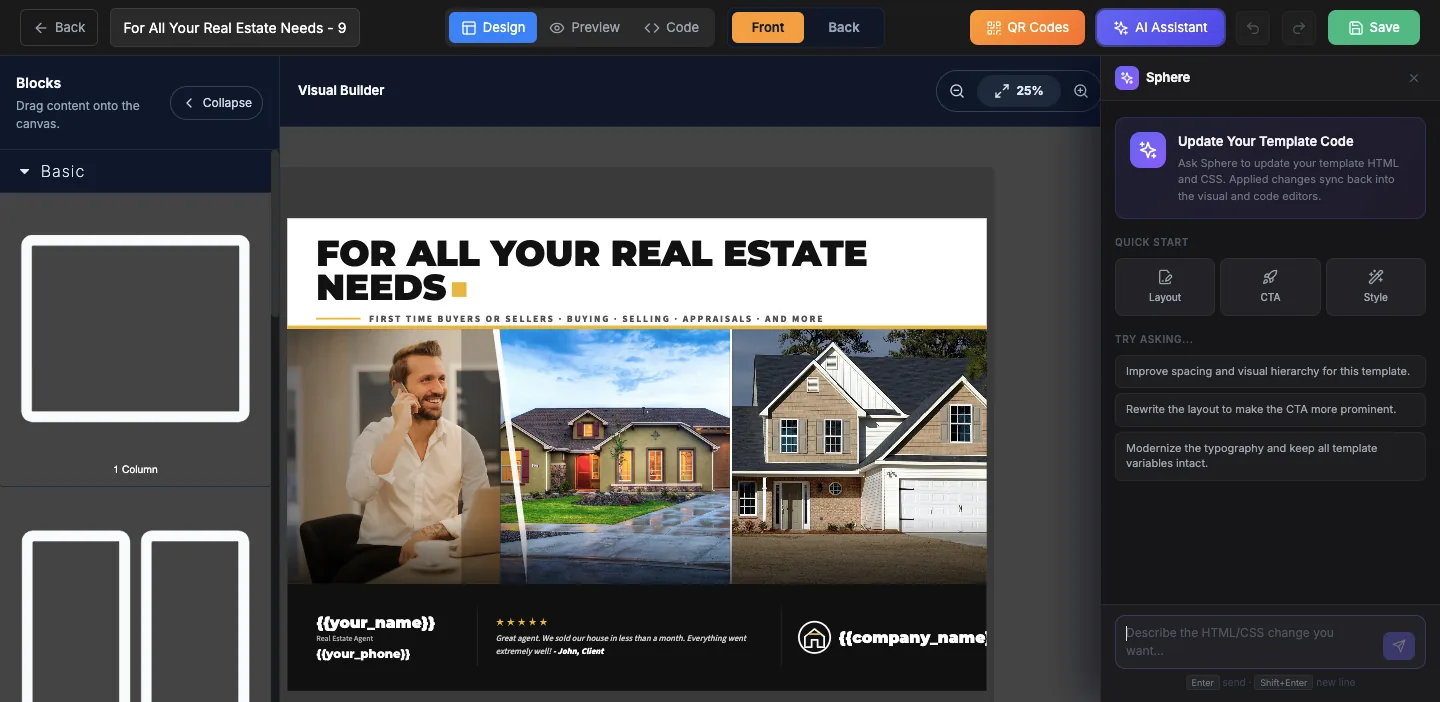
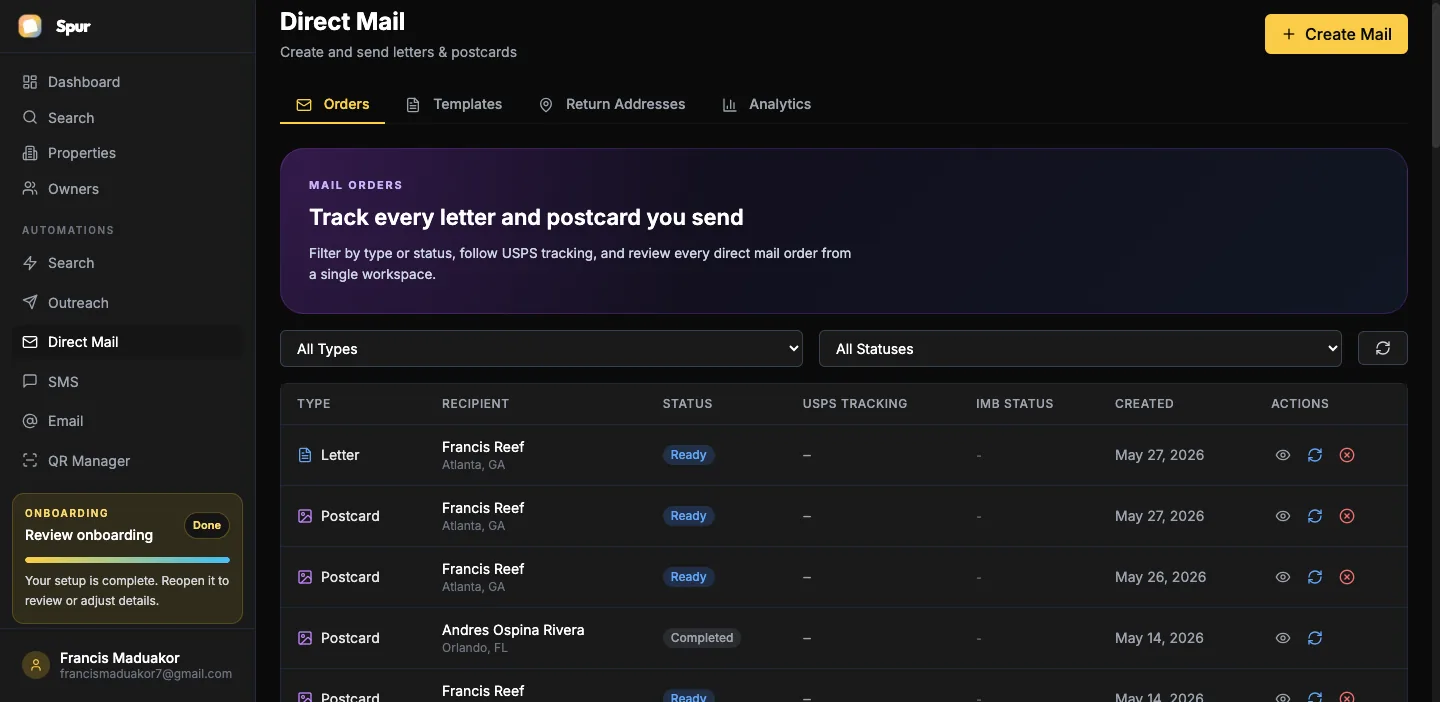
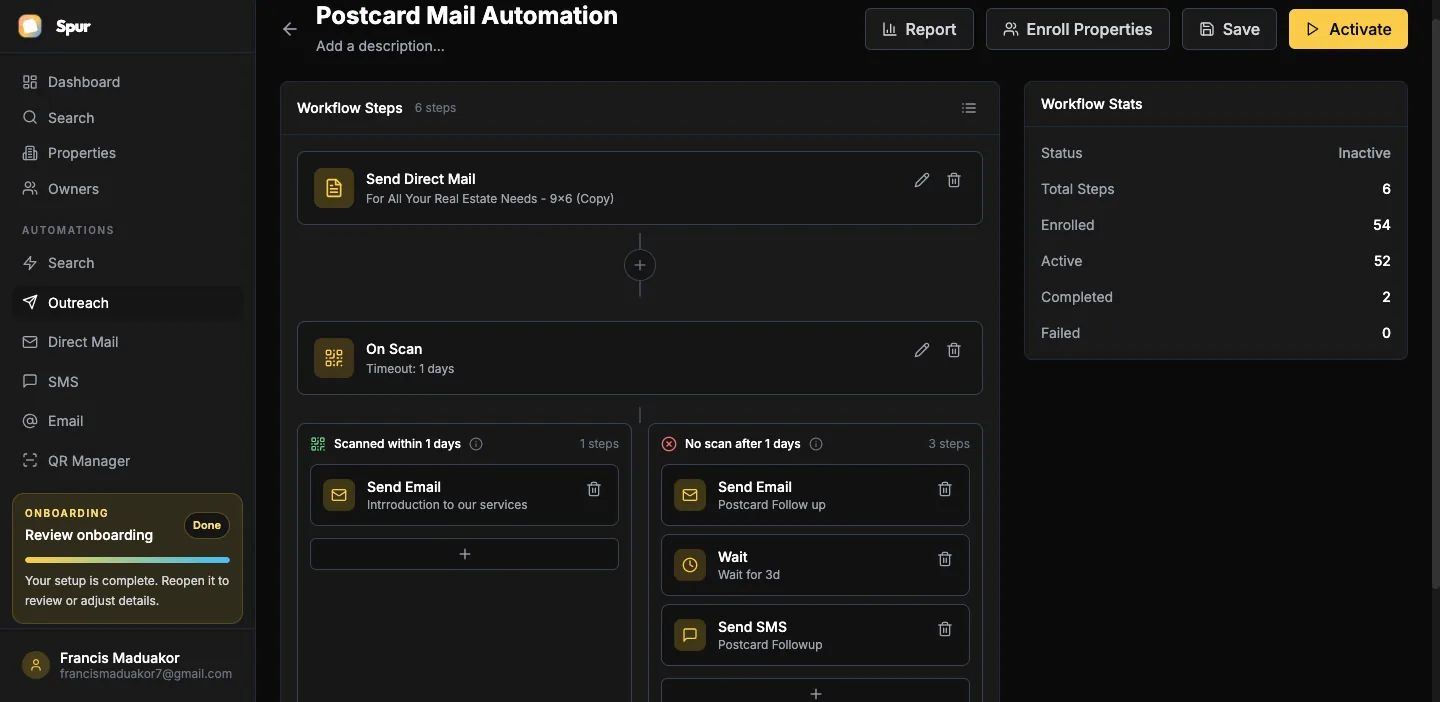
See it in Spur
A seller-finance list in Spur
Sample free-and-clear rentals in Asheville held 15+ years. Names are partly masked.
Asheville, NCNo mortgageOwned 15+ yrsAbsentee
- Walter D.710 Cherry StOwner across townFree and clearOwned 26 yrs
- June & Hank O.42 Pearson DrOwners in HendersonvilleDuplexOwned 31 yrs
- Ray B.1508 Haywood RdOwner in CharlotteFree and clearRented
- Patricia L.19 Maney AveOwner in FloridaOwned 22 yrsOut-of-state
- Hill Family LLC300 State StManager in AshevilleTriplexOwned 18 yrs
AI draft for Walter D. · 710 Cherry St
Dear Mr. Dalton,
I'm Eli, and I buy rental homes in West Asheville. I'm writing about your house at 710 Cherry Street, which it looks like you've owned for about 26 years.
If you've thought about selling but don't want to give up the income, here's another option. Rather than a one-time payment, I'd pay you monthly, with interest, secured by the house, much like a bank would. For example, at full price with 10% down, you could receive about $1,400 a month for years, without tenants, repairs, or vacancies.
Every situation is different, and I'd encourage you to talk it over with your accountant. Scan the code to see sample terms for your home.
Eli Warren · (828) 555-0145
Sample data for illustration. Your results depend on your market and filters.
Playbook
How to find sellers open to owner financing
In a seller-financed sale, the owner acts as the lender. The buyer makes a down payment, and the seller receives monthly payments with interest, secured by a note and a mortgage or deed of trust on the property. For an investor, it means buying without a bank. For the seller, it can mean a higher price, steady income, and less work than being a landlord.
Seller financing is easiest when the owner has no mortgage. An owner who still owes money usually has to pay off that loan at closing, which a seller-financed deal doesn't provide. Start with free-and-clear properties, then look for owners who value income over a lump sum: long-time landlords, owners near retirement, and owners of properties that are hard to finance with a bank.
Taxes are often part of the appeal. When a seller receives payments over time, they may be able to report the gain under the installment method rather than all in one year. You shouldn't give tax advice, but encouraging the owner to ask their accountant often moves the conversation forward.
Lead with a simple example. Many owners have never considered carrying a note, and an example with a price, down payment, interest rate, and monthly payment makes it real. Keep the numbers reasonable and clearly labeled as an example.
Use a real estate attorney and a title company to draft the note and security instrument, and use a loan servicer if both sides want one. Seller-financing rules are stricter when the buyer will live in the home; as an investor buying for business purposes, you'll typically face fewer requirements, but confirm with an attorney in your state.
Expect a longer conversation than a cash deal. Plan for several letters and a patient follow-up schedule.
Structure matters as much as price. Sellers usually care about the down payment, the interest rate, and how long payments last, so be ready to offer a few options. A larger down payment with a shorter term often appeals to cautious owners; a lower down payment with a higher price may appeal to owners focused on total income.
42×return on a year of Spur Team from one $25,000 deal
One deal on terms can pay for itself for years.
- Spur Team: $588/yr billed annually
- 250 free-and-clear owners × 3 letters = 750 at $1.39 = $1,043
- One seller-financed purchase worth $25,000 in equity and cash flow = 42× your subscription
Example math. Terms, cash flow, and equity vary widely by deal. Run your own numbers →
One tool, not four
Spur vs. the usual seller-finance prospecting stack
What you needThe usual waySpur
Free-and-clear and hold-time filtersA separate data subscription✓ Built in
Owner contact infoSeparate skip tracing✓ Built in
Letter with a sample paymentGeneric "cash or terms" postcard✓ Built in
Delivery trackingGuessing when to call✓ Built in
Patient follow-up scheduleCalendar reminders✓ Built in
FAQ
Seller financing questions
What is seller financing?
The owner acts as the lender: the buyer pays a down payment, then monthly payments with interest, secured by the property. It can mean a higher price and steady income for the seller.
How do I find properties for seller financing?
Start with free-and-clear properties owned 15+ years, then stack absentee ownership or rental use. Spur filters for all of these in one search.
Can an owner with a mortgage offer seller financing?
It's harder. Their existing loan usually must be paid off when they sell. Free-and-clear owners are the best fit for a simple seller-financed sale.
What should a seller financing letter say?
Name the property, explain the idea in a sentence, and give a clearly labeled example of the down payment and monthly income. Invite them to discuss it with their accountant.
Are there rules for seller financing?
Yes. Rules are stricter when the buyer will live in the home. Investors buying for business use typically face fewer requirements, but always use an attorney and title company.
Keep exploring
Related plays and guides
Start in minutes. No card required.
Offer the deal no cash buyer is offering.
Find free-and-clear owners in your market and mail your first seller-financing letter today.
Find seller-finance owners — freeFree forever plan · No card · 20 property searches a month
Prefer a walkthrough? Book a demo