Stories of storm chasers who promise a "free roof," collect a deposit, and vanish make homeowners suspicious of every roofer.
Roofing play · Insurance claims
Insurance claim roofing leads, built on honest inspections and good documentation.
After a storm, many homeowners don't know whether they have damage, whether it's worth a claim, or how the process works. Spur helps you reach them with a clear, compliant offer: a free inspection, photos of every slope, and a plain explanation of their options, mailed before claim deadlines pass.
Free forever plan · No card · 20 property searches a month
USPSFirst-Class
Diane Castillo1418 Canyon Ridge DrSan Antonio, TX 78258Scan for a free photo report
Diane C. requested a photo report · 52 min ago
AI-written for this owner · Mailed in 2 days
Photo reportfor every inspection, shared with the owner
Claim windowreminders before policy deadlines
Compliantcopy that never waives deductibles or promises coverage
The problem
Claim-driven roofing has a trust problem, and it hurts honest roofers.
Most people file a roof claim once or twice in their lives. They don't know about deductibles, adjuster visits, or depreciation, and they freeze.
Many policies limit how long after a storm a claim can be filed. Homeowners who wait for a leak can miss it.
How it works
From list to mailbox in one workflow.
Five steps from a storm to a well-documented claim decision.
app.usespur.com
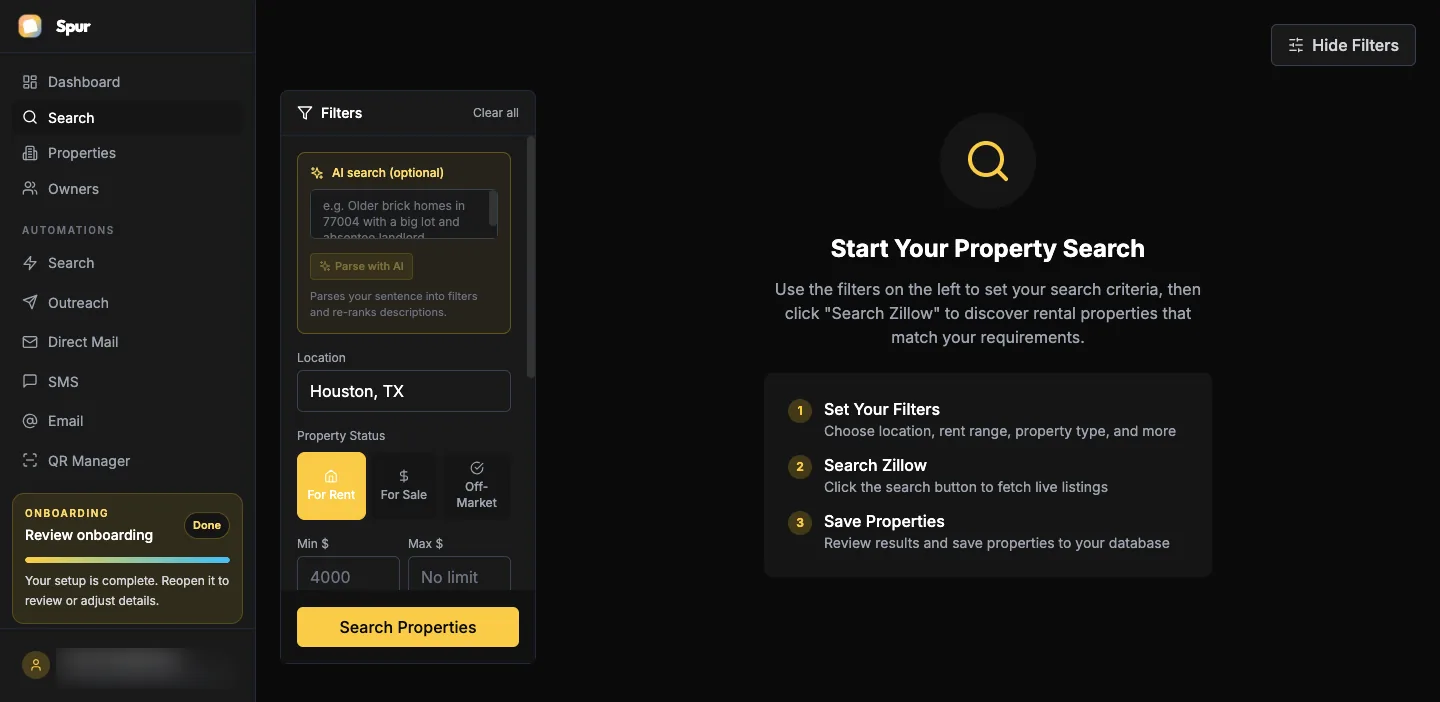
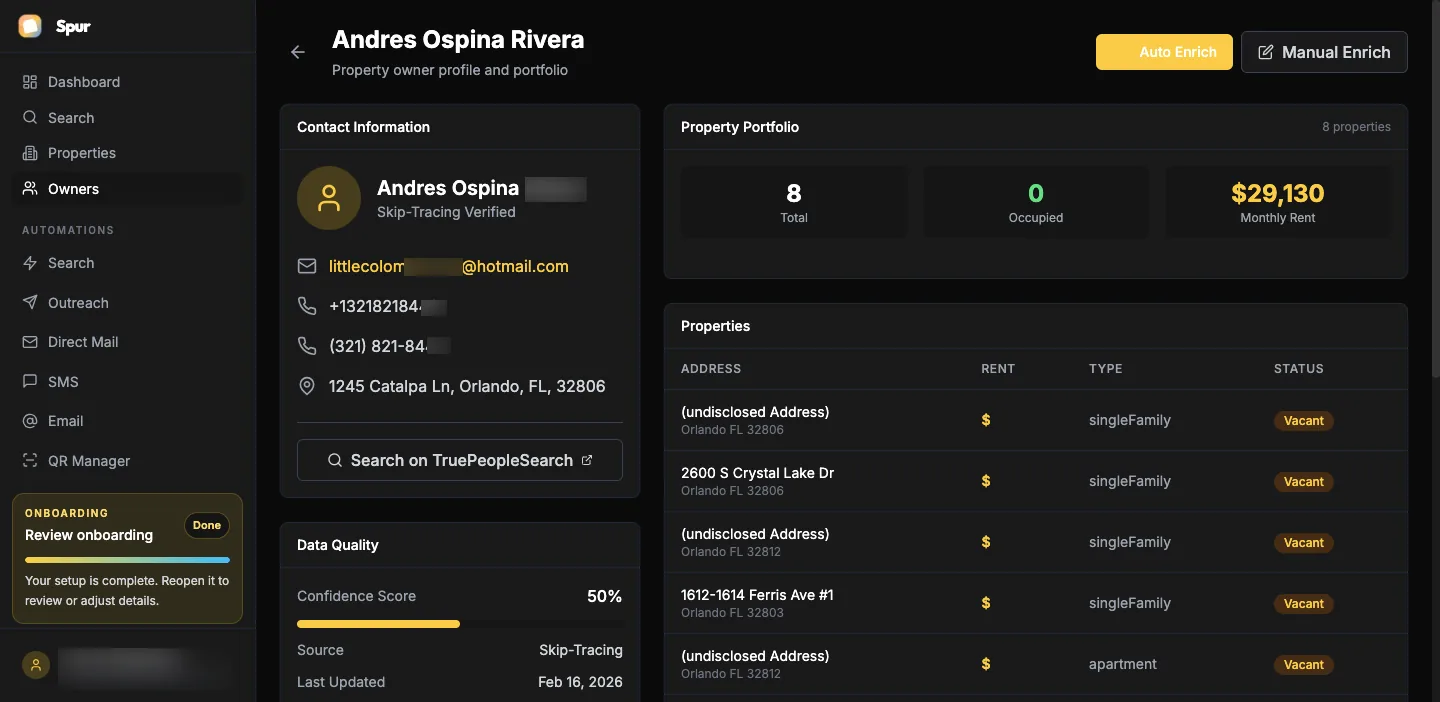
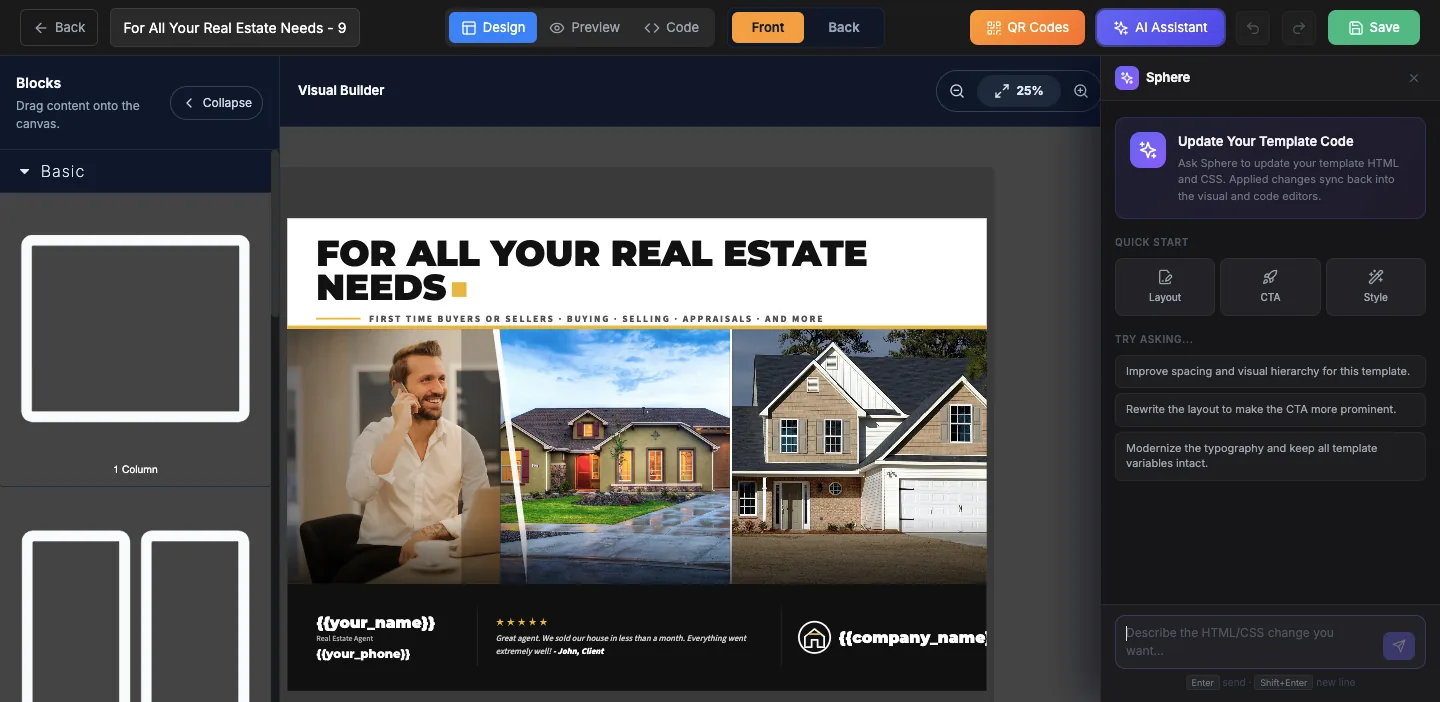
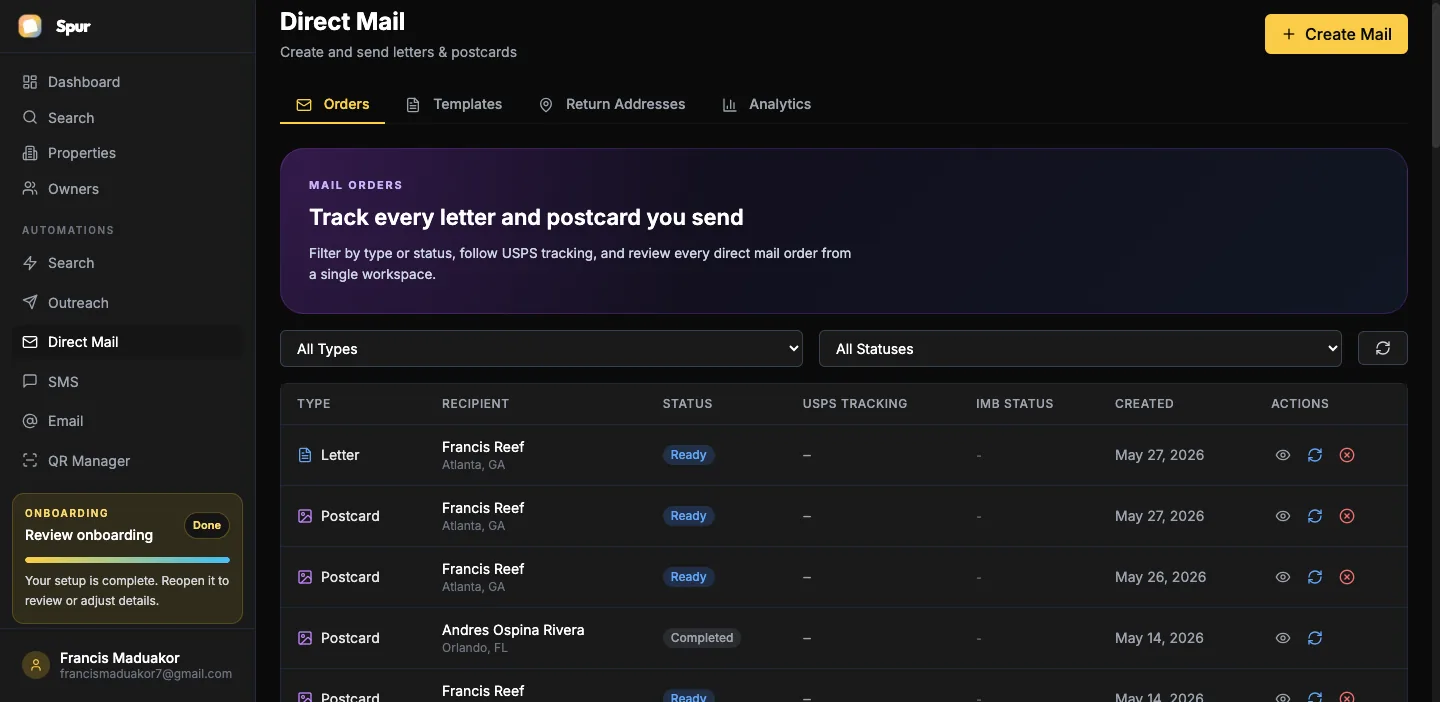
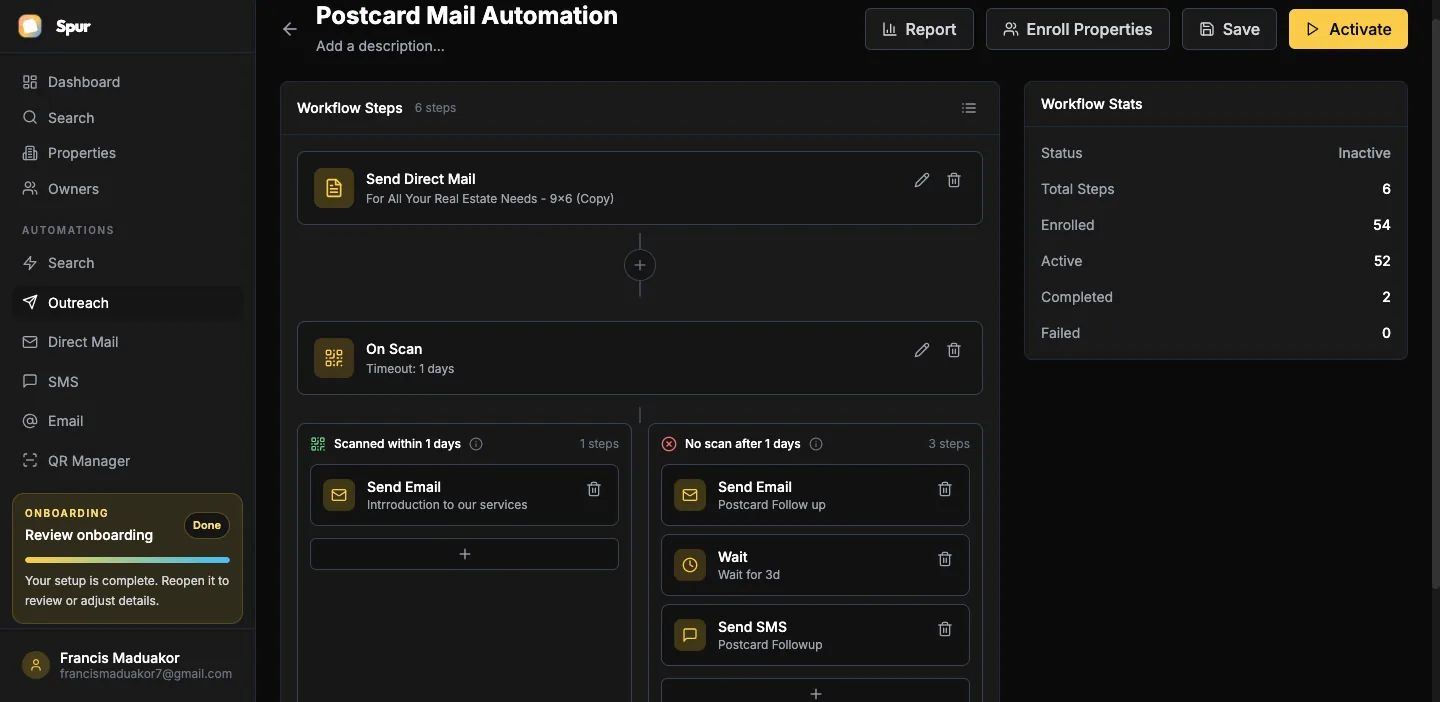
See it in Spur
A post-storm claim list in Spur
Sample homes in one San Antonio neighborhood after a May hail and wind event. Names are partly masked.
Zip 78258Storm May 21Single-familyOwner-occupiedBuilt 1995–2010
- Diane C.1418 Canyon Ridge Dr2,760 sq ft · built 2002Owned 17 yrs
- Luis & Ana G.1602 Bluff Spring Way3,240 sq ft · built 1999Two-storyOwned 20 yrs
- Michael T.20314 Stone Oak Pkwy2,190 sq ft · built 2005Owned 12 yrs
- Sharon W.1127 Fossil Ridge2,480 sq ft · built 1997Owned 23 yrsOwner out of state
- Ray P.1529 Hidden Bluff3,060 sq ft · built 2001Owned 19 yrs
AI draft for Diane C. · 1418 Canyon Ridge Dr
Dear Diane,
On May 21, hail and strong winds moved through Stone Oak. Storm damage to a roof is often hard to see from the ground, and many homeowners aren't sure whether it's worth calling their insurance company.
We'll inspect your roof for free and give you a photo report of every slope. If we find damage, we'll explain how the claim process usually works, what your deductible means, and what to expect from the adjuster's visit. Whether to file is entirely your decision, and we'll respect it either way.
Many policies limit how long after a storm you can file, so it's worth checking sooner rather than later. Scan the code to book an inspection.
Maria Vega · Hill Country Roofing · (210) 555-0184
Sample data for illustration. Your results depend on your market and filters.
Playbook
How to market insurance roofing work honestly
Insurance claims drive a large share of residential roof replacements, especially in hail and hurricane regions. The Insurance Information Institute reports that wind and hail damage is the most common cause of homeowners insurance claims. For a homeowner, though, a roof claim is unfamiliar and stressful, and the industry's reputation for aggressive storm chasers makes them cautious. The roofers who win this work over the long run are the ones who make the process clearer, not the ones who make the biggest promises.
Lead with documentation. A free inspection with a photo report of every slope is useful whether or not there's damage. It gives the homeowner something concrete to look at, it's what an adjuster will want to see, and it positions you as the expert in the room. Explain the basics in plain language: how a deductible works, what an adjuster visit looks like, and that the decision to file is theirs.
Know the rules, and stay well inside them. Texas Insurance Code chapter 707 prohibits contractors from paying, waiving, or rebating a homeowner's deductible, and several other states, including Colorado, have similar rules. In most states only a licensed public adjuster can negotiate a claim on the homeowner's behalf, so a roofer can document damage and meet the adjuster on the roof, but shouldn't advertise that they'll "handle your claim." Some states also give homeowners the right to cancel a roofing contract if the insurer denies the claim. Your mailers should never promise a free roof, imply guaranteed coverage, or offer to cover a deductible.
Time the follow-up around the claim window. Many policies set a deadline for filing wind and hail claims after the date of the storm. A reminder card a month or two before that window closes helps homeowners who meant to call and didn't. Encourage them to check their own policy rather than quoting a deadline you can't verify for them.
Done this way, insurance work builds referrals. A homeowner who felt informed and respected tells their neighbors, which matters more than any single storm.
17×return on a year of Spur Team from one $10,000 claim roof
Documented inspections turn into approved roofs.
- Spur Team: $588/yr, plus 600 storm-area homes × 2 letters = 1,200 letters at $1.29 = $1,548
- One approved $10,000 roof replacement = 17× your subscription
- Two approved roofs = $20,000, or 9× the software and postage combined
Example math. Claim approvals depend on the insurer, the policy, and the actual damage. Run your own numbers →
One tool, not four
Spur vs. the usual insurance roofing playbook
What you needThe usual waySpur
Homes in the affected areaDoor-knocking crews✓ Built in
Owner contact, including out-of-state ownersWhoever answers the door✓ Built in
Clear, compliant offer"Free roof" flyers✓ Built in
Letter printing and mailingOffice printer and stamps✓ Built in
Claim-window remindersNo follow-up✓ Built in
Insurance Claim Leads by the numbers
Why claim marketing has to be careful
#1
wind and hail damage is the most common cause of homeowners insurance claims
Ch. 707
of the Texas Insurance Code prohibits contractors from paying, waiving, or rebating a homeowner's deductible
17×
return on a year of Spur Team from one $10,000 claim roof
FAQ
Insurance claim roofing questions
How do roofers get insurance claim leads?
Reach homeowners in storm-affected areas with a free inspection and photo report, explain the claim process in plain language, and let them decide whether to file. Spur builds the list, writes the offer, and mails it within two business days.
Can a roofer help with an insurance claim?
A roofer can inspect, document damage, provide an estimate, and meet the adjuster on the roof. In most states only a licensed public adjuster can negotiate the claim on the homeowner's behalf, so check your state's rules.
Can I offer to pay the homeowner's deductible?
Not in many states. Texas, Colorado, and others prohibit contractors from paying, waiving, or rebating deductibles. Never put a deductible offer on a mailer.
Should I send a postcard or a letter for insurance work?
A sealed letter works well for the first touch because it can explain the process in more detail and feels more private. Postcards work for follow-ups and claim-window reminders.
How long do homeowners have to file a roof claim?
It depends on the policy and state, and many policies set a deadline for wind and hail claims. Encourage homeowners to check their own policy, and send a reminder before the typical window in your area closes.
Keep exploring
Related plays and guides
Start in minutes. No card required.
Be the roofer who made the claim process clear.
Pull the homes in the last storm's path and mail an honest inspection offer today. Free to start.
Find storm-hit homeowners — freeFree forever plan · No card · 20 property searches a month
Prefer a walkthrough? Book a demo